Author: telyadmin

  • Choosing Tax Preparation Support in Austin: A Record-Readiness Decision Guide

    Choosing Tax Preparation Support in Austin: A Record-Readiness Decision Guide

    Choose the support path before gathering documents

    Choosing tax preparation support starts with identifying the work that is blocking your tax-planning review. A bookkeeper or packet-preparation provider can organize records and expose missing support. A credentialed tax professional must evaluate rule-dependent questions and exercise professional judgment. A return preparer compiles and files supported historical activity after the needed decisions and records are ready.

    These services can occur in sequence, but they have different handoff points. Begin by asking whether the problem is retrieval, interpretation, or filing readiness:

    Immediate bottleneck Appropriate first conversation Handoff result
    Records are scattered, duplicated, or difficult to match to a period Bookkeeper or tax packet preparation provider An organized tax packet, document index, and list of gaps
    The facts are available but their tax treatment or filing effect is unclear Credentialed tax-planning review Current-rule verification and professional judgment on the identified questions
    The historical activity and required decisions are supported Tax return preparation Compilation and filing of the applicable return

    One Austin provider distinguishes preparation as reporting activity that already occurred during a tax year from planning as forward-looking, ongoing decision-making. Use that distinction when deciding where to send the next question. Do not ask an organizer to determine a filing position, payment, deadline, deduction, or Texas requirement, and do not ask a return preparer to infer unresolved facts from an unlabeled folder.

    At intake, state the entity, applicable filing period, current record condition, and the outcome you need from the next professional. That short description gives each provider a defined scope without turning the handoff into a tax conclusion.

    Decide whether tax packet preparation fits your current needs

    Use a simple intake test before requesting support:

    1. Define the requested outcome. Decide whether you need records arranged, a rule-dependent issue reviewed, or a supported return compiled.
    2. Identify the blocker. Separate missing documents from questions that remain after the documents are found.
    3. Set the handoff boundary. Tell the next provider which items are factual, which are reported by the owner or bookkeeper, and which require professional judgment.
    4. Confirm the next deliverable. Ask whether the engagement will produce an organized packet, a review agenda, or return preparation based on completed decisions.

    Packet-preparation support fits when the records exist but are difficult to retrieve, compare, or explain. A credentialed tax-planning review fits when the issue involves entity treatment, Texas, multistate activity, payroll, an information return, a filing period, a deadline, a payment, or tax treatment. According to the IRS, an entity’s form determines the income-tax return form the business must file, so uncertain entity facts belong in professional review rather than an organizer’s conclusion.

    Return preparation fits only after the historical activity is sufficiently supported and the decisions needed for filing have been reviewed where necessary. The selected checklist guidance recommends tax-professional help for payroll, contractors, deductions, multistate activity, or unclear records.

    Before contacting a provider, write three lines: what is available, what is missing, and what must be decided. Those lines help you choose the first support path and prevent one provider from being asked to perform another provider’s function.

    Build a status-labeled tax packet and document index

    Use the document index to decide what happens next, not to make a tax determination. Start each line with the business question or requested outcome, then record the period, source, current support, and person responsible for the next step.

    Decision field What to record
    Business question The neutral issue or requested outcome
    Applicable period The period shown by the record or reported by the owner
    Source The system, document, or person supplying the information
    Current status Confirmed record, assumption, needs documentation, open question, or professional judgment
    Next action Locate, clarify, verify, or review
    Responsible reviewer Organizer, bookkeeper, credentialed tax professional, or return preparer

    Use this routing sequence for each line:

    1. Locate. Send missing or scattered records to the organizer or bookkeeper.
    2. Clarify. Record owner-reported facts and identify what remains uncertain.
    3. Verify. Send entity, Texas, multistate, payroll, filing-period, information-return, payment, deadline, and tax-treatment questions to a credentialed tax professional.
    4. Prepare. Provide supported historical activity and reviewed decisions to the return preparer when filing work is needed.

    This approach keeps the service boundary visible. A record can be useful for organization while its tax effect remains unresolved.

    Gather the current-period financial record set

    Use the financial-record intake to describe what is available and where it came from. Begin with current-period bookkeeping, income summaries or profit-and-loss statements, categorized expenses, relevant third-party forms, payment history, payroll summaries where applicable, asset support, prior-period context, and forecasts that need review.

    For each category, record the period shown, the source location, whether the item is complete or partial, and the next action. A selected Austin provider identifies income summaries, categorized expenses, applicable payroll summaries, and relevant 1099 forms as typical meeting records. A comprehensive small-business checklist can also include business details, assets, contractor documents, prior returns, and estimated payments.

    Keep forecasts and owner-reported information visibly separate from historical bookkeeping. If a record is incomplete, identify the missing support rather than treating the category as ready for filing. This intake describes the work needed; it does not establish a tax position or return conclusion.

    Index estimated payments as records, not conclusions

    Include estimated-payment information in the intake when it may affect the requested review. Your first task is to show the receiving provider what evidence exists and which questions remain, not to decide whether a payment obligation applies.

    List the payment date, amount shown, period identified by the source, payment system or payee, and location of the confirmation or bank record. Mark a payment as a confirmed record only when supporting evidence is available. Identify remembered or reported payments separately.

    The IRS states that self-employed individuals generally must file an annual income tax return and pay estimated taxes quarterly; applicability and current requirements depend on the business and filing period. Ask a credentialed tax professional to verify whether that general rule applies, how the payment information should be treated, and whether any timing or amount question remains.

    Tell the organizer to locate and index evidence. Tell the credentialed reviewer to address applicability and current rules. That division keeps payment records useful without turning the intake into a payment conclusion.

    Separate payroll and contractor records before review

    Describe employee and contractor information as two separate workstreams when requesting support. This lets an organizer assemble the records without asking that provider to decide classification or filing obligations.

    For employee payroll, identify available wage records, payroll summaries, payment dates, payroll-tax payment records, proof of payment, and filed payroll forms where applicable. The selected guidance recommends retaining Forms 940 and 941 and corresponding state payroll-tax forms, subject to current-rule verification. For contractor activity, identify payment records separately and note the amount, date, payee, and source where available.

    The selected employment-record guidance says businesses with employees or independent contractors need records of worker payments, payroll taxes paid, and required employment documents; specific retention and filing requirements need current-rule verification. The IRS says information-return obligations can arise from payments made and, in some situations, payments received.

    Assign the work clearly: record retrieval and separation can go to packet preparation or bookkeeping; classification, information-return, payroll, Texas, and filing-period questions go to a credentialed tax professional. Ask the return preparer to use only the records and decisions that have reached the appropriate handoff stage.

    Document assets, entity facts, and activity that may change the review

    Use the intake to identify facts that may require a different level of support. Asset records can be organized by a bookkeeper or packet-preparation provider, while their tax treatment belongs with a credentialed tax professional. For each asset, identify the available purchase support, cost shown on the record, date placed in service if available, and applicable period.

    Record the entity form reported by the owner and identify its source. The IRS identifies sole proprietorships, partnerships, corporations, and S corporations as common business forms and notes that LLCs are allowed by state statute. It also states that an entity’s form determines the income-tax return form the business must file. If the entity information is uncertain, send the fact and its source for professional review rather than asking an organizer to resolve it.

    For activity outside Texas, report where work, customers, or workers were located and the period involved. Ask a credentialed tax professional to determine whether current Texas or multistate rules require further analysis. The intake should therefore name the fact, source, and requested reviewer, not state a filing position or obligation.

    Turn gaps and uncertainty into a professional-review list

    Finish the service-selection handoff with a short review brief for issues that cannot be resolved by locating records. The brief should help the credentialed tax professional start with the relevant facts rather than repeat the organizer’s work.

    Use these fields:

    Brief field Handoff purpose
    Issue Name the neutral topic and applicable period
    Available facts Identify the records and reported information
    Missing support State what has not been located or verified
    Question for review Ask what current-rule verification or professional judgment is needed
    Timing note Identify an event or possible deadline to verify without asserting applicability
    Prior work State whether bookkeeping or packet preparation remains incomplete

    Send document-retrieval gaps back to the organizer. Send entity, Texas, multistate, payroll, information-return, filing-period, payment, deadline, and tax-treatment questions to the credentialed tax professional. After those questions are addressed, provide the supported records and reviewed decisions to the return preparer if filing work is needed.

    Do not request a preferred tax outcome in the brief. The purpose is to make the next provider’s responsibility, inputs, and boundary clear.

    Arrive ready for a clearer tax-planning review

    The right preparation outcome is not a folder that looks complete. It is a clear choice about what happens next: organize records, obtain credentialed review, or prepare a return from supported historical activity.

    The IRS says keeping filing documents and tax forms in one place can help with accurate preparation and avoiding errors that could delay a refund. Use that principle to make your next service conversation more efficient:

    • Identify the current-period records you can locate and the records still missing.
    • Separate document-retrieval work from questions requiring professional judgment.
    • Keep payroll and contractor information distinct.
    • Bring payment confirmations, asset support, and bookkeeping reports that are available.
    • Put entity, Texas, multistate, payroll, filing-period, information-return, deadline, payment, and tax-treatment questions on the review agenda.
    • Ask a return preparer what additional supported records or reviewed decisions are needed before filing.

    The selected Austin provider characterizes accurate preparation and planning as complementary. For your business, begin with the support path that addresses the present bottleneck, then move to the next path only when the records and questions are ready.

    Frequently asked questions about tax packet preparation

    How is tax packet preparation different from tax return preparation?

    Packet preparation organizes current-period records and open questions for review. Return preparation compiles and files a completed return from supported facts and reviewed decisions.

    What should I include in a tax packet for a business review?

    Include current bookkeeping, income support, expense records, estimated payment confirmations, payroll summaries, contractor records, asset support, prior-period context, and any forecasts you need reviewed.

    How should I label items in the document index?

    Use clear statuses such as confirmed record, assumption, needs documentation, open question, and professional judgment. Add the applicable period, source, missing support, and the question that still needs review.

    When should a credentialed tax professional review an item?

    Route entity, Texas, multistate, payroll, information-return, filing-period, payment, deadline, and tax-treatment questions for current-rule verification and professional judgment.

    What if I have estimated-payment or payroll records but not all confirmations?

    Keep what you have and mark the gaps. List the payment date, amount, source, and period for each confirmation, then flag anything missing for follow-up.

    Do contractor records belong in the same folder as payroll records?

    Keep them separate in the index and in the packet. Track employee wages and contractor payments as different record groups so classification questions stay visible for review.
  • How to prepare for a small-business tax-planning review in Austin

    How to prepare for a small-business tax-planning review in Austin

    Decide whether a tax-planning review is the right next step

    A tax-planning review is a practical next step when your healthcare business is about to change, or when the records behind a change are incomplete. The goal is not to arrive with a claimed tax result. It is to give a credentialed tax professional enough current facts to identify the questions that need judgment before you act.

    One Austin tax-practice source distinguishes backward-looking tax preparation from forward-looking planning. Preparation generally organizes activity that already occurred. Planning focuses on decisions still being considered during the year. That distinction matters if you are weighing an equipment purchase, a hire, a compensation change, an ownership event, or an unusual transaction.

    Seek a review when any of these apply:

    • A planned purchase, financing arrangement, or business-use date is not yet settled.
    • Staffing, payroll and compensation, benefits, or contractor records have changed.
    • Ownership activity, distributions, compensation, or a transaction outside normal operations needs to be documented.
    • Your business has activity outside Texas or questions that may create multistate tax questions.
    • You do not know which entity, period, jurisdiction, or source record governs an issue.
    • You have an estimated tax, Texas franchise tax, notice, or applicable-deadline question that needs current guidance.

    A productive reviewer should ask to see records and receipts and ask questions about income, deductions, and credits, according to the IRS. Bring organized information, but keep the conclusion open: tax treatment, filing positions, deadlines, and obligations depend on current rules and your specific facts. When a material fact is uncertain, route it to credentialed tax professional judgment before acting.

    Build one source-record packet around the decision

    Build one source-record packet for each decision or event rather than sending disconnected reports, receipts, and messages. A packet is an organizing tool, not proof of compliance and not a tax conclusion. Its purpose is to make the relevant facts, gaps, and questions visible during review.

    The IRS says a recordkeeping system should summarize business transactions, ordinarily through business books such as journals and ledgers. Supporting documents back up those entries. A planning packet adds a clear label to each item so the reviewer can see what is historical, what is projected, and what still needs an answer.

    Use this header on each packet:

    Packet field What to enter Immediate use
    Business period The current period the item concerns Keeps current activity separate from prior-year history
    Entity The business entity connected to the item Prevents records from being mixed across entities
    Jurisdiction Federal, Texas, or another state involved Routes federal and Texas considerations separately from multistate tax questions
    Decision or event Purchase, hire, ownership activity, payment, or unusual transaction States why the item is being reviewed
    Source Invoice, bank record, payroll summary, contract, report, or forecast Shows where the information came from
    Status Confirmed fact, assumption, or unresolved question Signals whether professional judgment is needed

    For each packet, add a short issue statement: “We plan to do this; these are the records available; these are the facts still unknown.” A planning-workpaper approach can also identify required records, options to be reviewed, deadlines to confirm, expected impact as a question rather than a promise, and risk limitations. Keep the packet focused on one decision so a reviewer can trace the source record and ask targeted follow-up questions.

    Separate confirmed records from forecasts and unresolved questions

    Use three status labels consistently. The labels reduce confusion between what your records show and what you expect to happen.

    Confirmed facts are supported by current-period records. Purchases, sales, payroll, and other transactions generate supporting documents. Examples include sales slips, paid bills, invoices, receipts, deposit slips, and canceled checks. For a confirmed fact, identify the record, date, amount, entity, and business period.

    Assumptions describe a forecast or incomplete input. For example, a planned hire may have an expected start date and compensation figure that has not been finalized. Label it as an assumption rather than presenting it as a completed payroll event. State who supplied the forecast and when it should be updated.

    Unresolved questions are matters you cannot answer from the records alone. They may concern tax treatment, a deadline, a jurisdiction, a worker relationship, a business-use percentage, or an election. Do not turn an unresolved question into a tax conclusion. Write the question plainly and ask your credentialed tax professional to review it.

    A useful entry might read: “ASSUMPTION—Entity A expects to acquire specified equipment during the current period; amount and financing details are based on a vendor proposal dated [date]. UNRESOLVED QUESTION—What records, timing, and current federal and Texas considerations should be reviewed before the acquisition?”

    This approach preserves the distinction between a business forecast and a completed transaction. It also gives the reviewer a direct action: confirm the facts, request missing support, or provide credentialed tax professional judgment.

    Collect current-period records that show your healthcare business activity

    For federal tax purposes, the records needed can depend on the business and the issue under review. Start with current-period records that show the activity of your practice, clinic, or healthcare-related business. The IRS states that business books must show gross income, deductions, and credits.

    Organize these categories by business period, entity, source, and status:

    • Patient-service revenue and payer receipts: income summaries, invoices, deposit information, payment-platform reports, and records showing the amounts and sources of gross receipts.
    • Operating expenses and supplies: categorized expense records, paid bills, invoices, receipts, account statements, and proof of payment. For expenses, retain the payee, amount, proof of payment, date, and a business-purpose description.
    • Payroll and compensation: payroll summaries, wage-related records, compensation activity, and documents supporting any changes. Identify the entity and pay period.
    • Benefits: current-period benefit invoices, payment records, and any pending change that requires review. Do not assume a treatment from the invoice alone.
    • Contractor records: agreements, invoices, payment support, and relevant contractor records. Flag worker-related questions for professional judgment rather than labeling a relationship yourself.
    • Equipment and other assets: invoices, financing details, payment records, acquisition dates, improvements, and use information.
    • Ownership activity: records of ownership changes, owner compensation, distributions, contributions, or other activity that may affect the review.

    The IRS recommends keeping supporting documents orderly, for example by year and type of income or expense. Electronic records follow the same basic recordkeeping principles as hard-copy records. A clear folder structure is enough: current period first, then entity, then category, with source files retained behind each summary.

    If a category is absent, say so. If a record is still being requested, label it unresolved. That is more useful than silently filling a gap with an assumption.

    Document planned changes before asking about tax treatment

    A planned change deserves its own packet because the relevant facts may not appear in ordinary bookkeeping yet. Document the commercial decision first. Then ask what current rules and records need review.

    For a planned purchase, gather the vendor proposal or invoice, expected amount, payee, expected payment method, financing details, intended business purpose, expected acquisition date, and expected date of use. For a completed purchase, retain documents identifying the payee, amount, proof of payment, date incurred, and item description.

    For a planned hire or compensation change, record the expected role, entity, timing, expected compensation or benefit terms, and the source document. Label any undecided item as an assumption. Ask the reviewing professional what payroll and compensation, contractor records, federal and Texas considerations, and applicable deadlines require review.

    For ownership activity or an unusual transaction, state what happened or is proposed, the parties involved, dates, amounts, governing documents available, and the business reason. Identify whether the fact is confirmed or still expected. Do not characterize the tax effect yourself.

    End every planned-change packet with three lines:

    1. Decision requested: what you are considering.
    2. Records attached: what supports the known facts.
    3. Professional-review question: the exact conclusion, timing issue, or current-rule question you need reviewed.

    This format keeps planning practical. It gives your credentialed tax professional a defined question and a traceable source record, while preserving uncertainty where it belongs.

    Do not treat an equipment invoice as a tax conclusion

    An equipment invoice confirms that a vendor quoted or billed an item. It does not, by itself, establish the item’s tax treatment. This distinction is especially important for healthcare businesses acquiring clinical equipment, furnishings, technology, or other business property.

    The IRS says asset records are needed to compute annual depreciation and gain or loss on disposition. Gather records of acquisition, cost, improvements, use, relevant deductions, and any disposition. For qualifying property, the IRS ties depreciation to placing the property in service for business or income-producing use. Depreciation is an annual deduction that recovers the cost or other basis of certain property over its period of use.

    Property used partly for business or investment and partly personally has an additional boundary: only the business or investment-use portion may be depreciated.

    Your packet should therefore identify:

    • Whether the item is planned, acquired, or placed in service.
    • The invoice, financing, payment, and acquisition records available.
    • How the business expects to use it, including any mixed use.
    • Whether improvements, trade-ins, or later disposition are involved.
    • The unresolved question for professional review.

    Ask a credentialed tax professional whether a Section 179 election may apply. The IRS describes it as subject to qualification, dollar-limit, and taxable-income conditions. Current limits and qualification rules require verification. The direct action is simple: provide the asset facts and records, then wait for credentialed tax professional judgment before treating the purchase as a particular deduction or election.

    Use the prior-year return for context, not as a substitute for current facts

    Bring a prior-year return when available, but treat it as context rather than a replacement for current-period records. One source notes that a prior-year return can help an accountant become familiar with a business’s financial health, while not presenting it as a required document.

    The prior return can help identify historical items to discuss. It cannot confirm that the current period matches the prior one. A new payer arrangement, a changed staffing model, an equipment acquisition, new ownership activity, or activity in another jurisdiction should be documented with current records and forecasts.

    Add these current reports when they are available:

    • An income statement, also called a profit and loss report, showing revenue streams and expenses for the current period.
    • A balance sheet showing assets, liabilities, and owner’s equity for the relevant period.
    • A cash flow statement summarizing cash management and cash generation for obligations or expenses.
    • Documentation of estimated payments when applicable, along with tax notices, asset invoices, financing details, and other records related to the decision under review.

    Create a short comparison note: “Prior-year return included for context. Current-period differences: [list].” Include changes in patient-service revenue, payer receipts, payroll and compensation, benefits, contractor records, equipment, supplies, ownership activity, or jurisdictions. If you cannot confirm a difference from source records, mark it as an assumption or unresolved question. The reviewer can then decide what additional information is needed.

    Prepare questions across federal, Texas, and multistate considerations

    Convert the unresolved items in your packet into a short agenda. Separate questions by jurisdiction so a federal issue is not confused with a Texas question or a possible multistate tax question. Current guidance, entity status, activity, records, and applicable deadlines all need confirmation.

    Federal considerations

    • Based on the confirmed facts and planned activity, what federal issues need review?
    • Are there estimated tax questions for the business or owner that require current guidance?
    • What records are needed to review payroll and compensation, benefits, contractor records, or an asset purchase?
    • Does a planned transaction raise a timing, depreciation, election, or other fact-dependent question?

    Texas considerations

    • Does the current entity and activity create a Texas franchise tax question that should be reviewed under current guidance?
    • Which current-period records and applicable deadlines should be confirmed for the entity?
    • Do payroll and compensation, contractor records, ownership activity, or an unusual transaction create a Texas-specific question?

    Multistate considerations

    • Did the business have revenue, services, personnel, property, payments, or another connection outside Texas that needs review?
    • Which jurisdictions may need current guidance, and what records show the relevant activity?
    • Are there registration, withholding, filing, or deadline questions that require credentialed tax professional judgment?

    Keep questions factual and narrow. “What applies?” is less helpful than “Entity B received payer receipts connected to activity outside Texas during the current period; which records and jurisdictions should be reviewed?” End each group with the boundary: confirm current rules and applicable deadlines with a credentialed tax professional.

    Turn organized facts into a more productive review conversation

    A practical next step is to bring one clearly labeled source-record packet for each material decision. Include current-period records, forecasts identified as assumptions, and concise unresolved questions. This helps a reviewer focus on the facts that changed instead of reconstructing them from scattered files.

    Choose an appropriate professional carefully. The IRS provides a searchable, sortable directory for federal tax return preparers with specified credentials or qualifications. The IRS also states that taxpayers remain responsible for information on their income tax returns regardless of who prepares them. If a paid preparer files a return, the IRS says the preparer must have a PTIN and must sign and include it on the return.

    Before scheduling, confirm what materials the professional wants, the business periods and entities to include, and which federal and Texas considerations need current review. Bring records and receipts, be prepared to answer follow-up questions, and keep tax conclusions open until the relevant facts and current guidance have been reviewed by a credentialed tax professional.

    Frequently asked questions about preparing for a tax-planning review

    What should I gather before a tax-planning review for my business?

    Start with current-period records that show income, expenses, payroll, assets, and any planned changes. Include invoices, receipts, deposit records, payroll summaries, contractor records, financing details, and prior returns if they help provide context. Keep the material organized by period, entity, jurisdiction, and source.

    How should I label facts, assumptions, and unresolved questions?

    Use confirmed fact for items supported by source records, assumption for expected but not completed activity, and unresolved question for anything that still needs credentialed tax professional judgment. That separation helps the reviewer see what is settled, what is forecast, and what still needs review.

    What records matter for equipment purchases and other assets?

    Gather acquisition documents, payment support, financing details, cost, improvements, and how the asset is used. Those records help review depreciation, business use, and any later disposition. A purchase invoice alone does not settle the tax treatment.

    Should I bring prior-year returns to the review?

    Yes, if available, but treat them as context rather than a substitute for current facts. A prior return can help the reviewer understand history, while current-period records show what has changed this year.

    What questions should I ask about federal and Texas considerations?

    Ask what current records are needed for estimated tax, payroll and compensation, contractor records, Texas franchise tax, and any multistate tax questions. Also confirm which applicable deadlines matter for your entity and activity.

    When does a planned change need professional review before I act?

    If the change involves a purchase, hire, ownership activity, unusual transaction, or activity outside your normal pattern, review it before acting. Those situations often depend on current rules, business facts, and record support that need credentialed tax professional judgment.

    How can a healthcare business organize records for review without creating confusion?

    Group patient-service revenue, payer receipts, payroll, benefits, contractor payments, equipment, supplies, and ownership activity into separate folders or tabs. Keep each item tied to the business period and source record so the reviewer can follow the facts quickly.

  • Dental Implant Cost: How to Compare a Component Price With a Complete Treatment Estimate

    Dental Implant Cost: How to Compare a Component Price With a Complete Treatment Estimate

    What Dental Implant Cost Should Represent

    Start by asking a scope question before a price question: What does this figure actually cover? A low headline number may describe one component of treatment, while a completed-treatment estimate may include the implant, connector, final tooth, and other services needed to complete the planned restoration.

    An implant estimate is not interchangeable with a quote for an implant post alone. The total can also depend on examination findings, imaging the provider determines is needed, preliminary procedures, the restoration selected, anesthesia needs, and insurance benefits. An online estimate can help frame questions, but it is not a treatment quote or price guarantee.

    For context only, one provider-published 2026 guide lists $3,000–$6,000 for one tooth when the implant post, abutment, and crown are included. That is not a universal price, national benchmark, or prediction of what your care will cost. It is a useful reminder that a meaningful comparison starts by confirming whether all three core restoration components are included.

    A personalized written estimate requires a dental professional to evaluate your situation and prepare a treatment plan. Until then, treat every number as a starting point for clarifying scope—not as the final cost of completed treatment. The right comparison is therefore not simply the lowest advertised figure; it is the estimate that clearly identifies the treatment being priced and the conditions that could change it.

    The Three Core Components to Identify in an Implant Estimate

    Treat the three core restoration components as the first three lines to locate in any estimate. This is a scope-reading exercise, not a way to determine which treatment is appropriate.

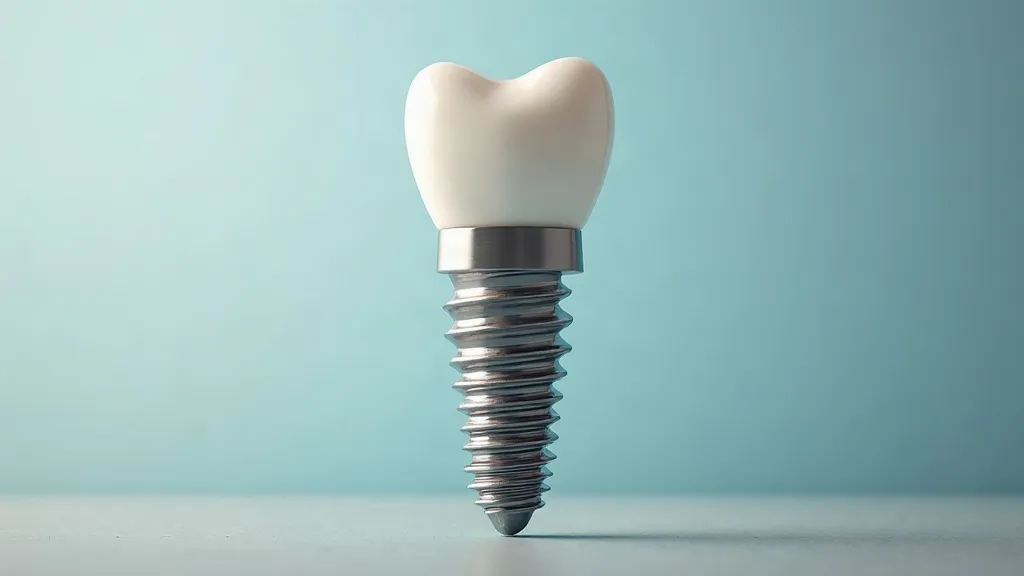
    1. Implant body: This is the portion surgically inserted in the jawbone in place of a tooth root. A dental implant system includes an implant body and an abutment; it may also include a fixation screw.
    2. Abutment: This connector extends into the mouth and supports the attached artificial tooth or teeth.
    3. Crown: The crown is the visible tooth portion of the restoration.

    Mark each component as named and included, named but separate, or not identified. A price described as an “implant” may refer only to the implanted body, while another estimate may use the same word for a package containing the abutment and crown. Those descriptions cannot be compared as equal totals until their scope is clear.

    The restoration arrangement also matters. A fixed artificial tooth can be attached to an individual implant abutment, and an implant can support several teeth joined in a bridge. A single-tooth component list therefore should not be assumed to describe a bridge or another restoration arrangement.

    When an estimate uses one bundled label, ask for the implant body, abutment, and final restoration to be identified in writing. The useful comparison is not which label sounds more complete; it is whether both documents price the same completed restoration.

    Why a Component Price Is Not the Cost of Completed Treatment

    Provider-published ranges illustrate why the label attached to a price matters. In one provider-published 2026 component table, the implant post is listed at $1,000–$3,000, the abutment at $400–$1,000, and the crown at $800–$3,000. The same guide lists $3,000–$6,000 for a single tooth when all three are included. These figures are provider-published examples, not universal pricing.

    A separate dental practice publishes an approximately $800–$2,500 range for the crown portion alone, depending on material and laboratory work, and notes that quoted ranges vary by region and practice. That example reinforces a practical point: even two prices for a “crown” may not represent identical services.

    Bundling also changes how an estimate reads. Whether an abutment or temporary crown is included in a crown fee can vary by practice. One practice says its crown fee usually includes scans or impressions, laboratory fabrication, and a temporary crown when needed, but those inclusions should be confirmed with the provider you choose.

    A quoted component price can therefore look lower simply because other stages are listed elsewhere or remain undecided. Review the description beside the number, not just the number itself. Confirm whether the fee is for a surgical component, a prosthetic component, a complete restoration, or a broader treatment phase.

    Do not try to build a personal total by adding internet ranges together. The line items may overlap, omit services, or apply to a different treatment scope. Instead, use published figures to recognize the difference between a component price and an estimate for the planned course of care.

    Use a Completed-Treatment Estimate Audit Before Comparing Prices

    Use the same four-status legend on every estimate: included, separate, contingent, or not identified. This completed-treatment estimate audit helps reveal whether a lower figure reflects a smaller stated scope rather than a lower price for the same treatment.

    1. Read the restoration lines first

    • Implant body
    • Abutment
    • Final crown, bridge, or other planned restoration

    2. Mark planning and production items

    • Consultation, diagnostics, and imaging the provider determines is needed
    • Scans or impressions and laboratory fabrication
    • A temporary restoration, when needed

    3. Mark items that may depend on findings

    • Extraction, bone grafting, sinus lift, or anesthesia
    • Adjustments and follow-up visits
    • Any charge described as pending, optional, or dependent on clinical findings

    4. Record the financial terms separately

    • The amount quoted for each stage
    • The payment timing for each stage
    • Whether the document identifies a fixed listed fee, an estimate, or a contingent item

    A written treatment plan may identify the proposed implant treatment, preliminary procedures, timeline, estimated costs, and restoration details. Transfer its line items into the four-status legend rather than trying to calculate a total from labels alone.

    For example, an estimate that names the implant body, abutment, and crown but leaves imaging, laboratory work, or a temporary restoration unmarked is not necessarily incomplete. It is incomplete for comparison until those items are identified as included, separate, contingent, or not identified. Ask for unclear items to be clarified in writing before comparing the document with another estimate.

    Treatment Factors That Can Change the Total Cost

    In an estimate audit, treatment factors belong in the contingent column until the provider confirms whether they apply. Their presence in a general cost discussion does not mean they apply to a particular reader.

    The number of teeth being replaced and the restoration type are treatment-planning considerations. A plan may use a single crown, a bridge, or a full-arch prosthetic. An implant can support several teeth joined in a bridge, so a cost comparison should identify the planned restoration rather than assume every tooth is priced as a separate single-tooth restoration.

    Costs can also vary with bone volume and density, preparatory procedures, implant and prosthetic choices, anesthesia needs, and applicable insurance benefits. Potential preparatory procedures cited as cost variables include tooth extraction, bone grafting, and sinus lift. Whether a procedure is needed can only be assessed through professional evaluation and, when the provider determines it is needed, diagnostic imaging.

    When a proposed estimate mentions an alternative restoration or an additional procedure, record three details: the affected line item, whether the item is confirmed or contingent, and the revised estimated amount. This keeps a possible future charge separate from the amount currently priced. It also avoids treating an unlisted procedure as included or assuming that a lower total has the same treatment scope.

    How a Consultation Leads to a Personalized Written Estimate

    The consultation is where the four-status audit can be completed with provider-specific information. It may include an oral examination and imaging such as X-rays or 3D CBCT; the provider determines what is needed. These steps may affect the proposed treatment, any preliminary procedures, and the estimate’s contingent items.

    A written treatment plan may identify the proposed implant treatment, preliminary procedures, timeline, estimated costs, restoration details, and the number and location of implants. Use it as the source document for your comparison record.

    Ask the provider to identify:

    • the implant body, abutment, and final restoration included in the estimate;
    • which diagnostic, laboratory, temporary, anesthesia, adjustment, and follow-up charges are included or separate;
    • which items remain contingent on findings;
    • the payment timing for each stage; and
    • whether estimated fees and exclusions can be provided in writing.

    A provider may issue a formal written plan detailing fees after the consultation; confirm this practice with the provider you choose. Without an examination, appropriate planning, and provider-specific fees, a general article or online tool cannot provide an individualized total.

    If the plan changes, compare the revised document with the earlier one line by line. Ask which line changed, whether the change follows a confirmed finding or remains contingent, and what amount is now estimated for that line.

    How Insurance Can Affect Out-of-Pocket Implant Cost

    Keep insurance information separate from provider fees in the estimate audit. The provider’s document identifies planned services and fees; the insurance contract determines applicable benefits. Coverage details—including exclusions, effective dates, deductibles, annual maximums, and waiting periods—can differ by contract.

    A waiting period is a period after plan purchase before benefits for certain treatment may become available. Waiting periods vary by plan, and treatment received during one may not be paid by the plan. One insurer says some plans may impose waits of 6–12 months for restorative services and often 12 months for major services such as crowns or dentures; that example is plan-specific, not a rule for every policy.

    For each planned procedure, record:

    • the procedure and expected service date;
    • any stated waiting-period, exclusion, deductible, annual-maximum, or effective-date issue;
    • the available estimate of benefits; and
    • the amount that remains the patient’s responsibility if benefits differ from the estimate.

    For plan-specific terms, consult the Evidence of Coverage or Certificate of Insurance and verify the procedure and date with the carrier. Benefit verification is not a guarantee of payment; the carrier makes the final claim decision.

    Do not subtract an expected benefit from a provider estimate and treat the result as final. Instead, retain both records: the treatment estimate for the planned fee and the benefit information for the contract terms that may apply. This makes it easier to see which part of an out-of-pocket calculation is a provider fee and which part depends on the insurer’s final claim decision.

    Leave the Consultation Ready to Compare the Full Scope

    Before comparing dental implant estimates, give every line item one status: included, separate, contingent, or not identified. Start with the implant body, abutment, and final restoration, then apply the same status to diagnostics, imaging, laboratory work, temporaries, anesthesia, follow-up, preparatory procedures, and insurance-related information.

    Keep the written treatment plan, the four-status record, and benefit information together. The treatment plan may identify estimated fees and restoration details, while benefit verification remains subject to the carrier’s final claim decision.

    A component price can be useful context, but it is not a completed-treatment total unless its scope is stated. Request clarification in writing when a line item, contingency, or payment stage is unclear before using an estimate to make a financial comparison.

    Dental Implant Cost Consultation Questions

    What should a dental implant estimate include?

    At minimum, check whether the implant body, abutment, and final crown are included. A clearer estimate also shows any diagnostics, imaging, lab work, temporaries, and follow-up fees that may be part of the plan.

    Why can one implant price be lower than another?

    The label may cover a different scope. Some fees include only one part of treatment, while others bundle more services or materials. The number of teeth being replaced, the restoration type, and the material choices can all change the total.

    Which treatment factors can add to the total cost?

    Costs can change if the plan requires extractions, bone grafting, a sinus lift, anesthesia, or a different implant or restoration option. Bone volume and density, along with the planned number of teeth, can also affect the estimate.

    How can insurance affect what I pay?

    Coverage depends on your specific plan. Waiting periods, exclusions, deductibles, annual maximums, and effective dates may all matter, and verification is not a guarantee that the claim will be paid.

    What should I ask for during the consultation?

    Ask for a written treatment plan that shows what is included, what is excluded, what is contingent on findings, and when payment is due. It is also useful to ask which charges could change after imaging or examination and whether benefits have been checked for the proposed procedure.

    Can an online estimate replace an in-person evaluation?

    No. An online figure can help you prepare questions, but it cannot account for the findings, fees, and coverage details needed for a personalized estimate.

  • Small Business Tax Deductions Checklist: Evaluate Each Expense With an Evidence Test

    Small Business Tax Deductions Checklist: Evaluate Each Expense With an Evidence Test

    Start with potential deductions and four clear review statuses

    A small-business tax deductions checklist should not tell you what to claim. Its job is to create a complete inventory of expenses that may deserve tax review, with enough evidence and context for a credentialed tax professional to evaluate them.

    Start every entry as potentially deductible, not deductible. Under IRS guidance, a business expense must be ordinary and necessary; an ordinary expense is common and accepted in the business field, while a necessary expense is helpful and appropriate rather than indispensable. Whether a particular payment meets those standards—and any additional requirements for the applicable tax period—depends on the facts and current rules.

    Use four statuses throughout the checklist:

    • Documented transaction: You have the transaction details and records showing what was paid, when, to whom, and for what business purpose.
    • Incomplete support: The expense appears in bookkeeping or a statement, but key support is missing, such as an invoice, receipt, payment confirmation, or business-purpose note.
    • Owner assumption: You believe the payment relates to the business, but the use, allocation, recipient, timing, or treatment has not been documented.
    • Current-rule or professional-review question: The facts are collected, but eligibility, limits, payroll treatment, mixed use, asset treatment, or another rule-dependent issue needs applicable-period review.

    This approach changes the central question from “What can I write off?” to “What do I know about this expense, what records support it, and what still needs review?” That distinction is especially useful for Austin owners preparing current bookkeeping, prior-year returns, payroll information, asset records, and forecasts for a planning conversation.

    Use the same evidence fields for every potential expense

    Create one checklist row for each expense group, vendor, reimbursement, asset, or recurring cost that may need review. Consistent fields make missing information visible quickly and keep unlike expenses comparable.

    For every entry, capture:

    1. Expense category: Use a plain-language label, such as supplies, rent, software, payroll, equipment, travel, or home-office cost.
    2. Business purpose: State what business activity, service, administration, operation, or revenue-producing work the payment relates to.
    3. Payee: Record the vendor, employee, contractor, landlord, lender, or other recipient.
    4. Amount: Note the amount paid or reimbursed and identify whether the figure is a single transaction, monthly total, or period total.
    5. Date or period: Record the transaction date and the tax or bookkeeping period it belongs to.
    6. Payment evidence: Link or attach the bank record, card statement, canceled check, electronic-transfer confirmation, or other proof of payment.
    7. Source documents: Include receipts, paid bills, invoices, sales slips, contracts, mileage records, payroll reports, or other documents that explain the transaction.
    8. Business and personal-use status: Mark business only, mixed use, personal component identified, or use not yet confirmed.
    9. Review status: Apply one of the four statuses above and write the next action.

    IRS recordkeeping guidance says expense records should identify the payee, amount paid, proof of payment, date incurred, and a description of the item or service showing its business connection. One document may not establish every detail. A card statement may prove payment, for example, while an invoice or receipt explains what was purchased and why it relates to the business.

    Use a short notes field for facts that change the review: “shared subscription,” “owner paid personally,” “reimbursement pending,” “used in clinic and at home,” or “invoice missing.” Do not fill a gap with a conclusion. Mark the gap and preserve the question.

    Trace each potential deduction from the books to its evidence

    Use your books as the starting point for an expense-by-expense evidence test. The IRS says a business may use a recordkeeping system suited to its operations if it clearly shows income and expenses. A transaction summary is ordinarily maintained in business books, such as accounting journals or ledgers; electronic records follow the same basic recordkeeping principles as paper records.

    For each expense category on the checklist, work through this trace:

    • Locate the ledger account and the underlying transaction or period total.
    • Compare the date, amount, payee, and category in the books with the payment trail.
    • Find the receipt, invoice, paid bill, contract, sales slip, or other record that explains the item or service.
    • Add a concise business-purpose note when the source document does not make that connection clear.
    • Mark any difference between the books and the available records as incomplete support, mixed use, or a review question.

    Supporting documents from purchases, sales, payroll, and other transactions can support book entries and tax-return items. Keep them orderly by year and income or expense type, but organize the checklist around the question each entry must answer: Does the record identify the payment and explain its business connection?

    Good records can help a business monitor operations, prepare financial statements and returns, track expenses and property basis, and support reported items. For a healthcare practice or another service business, test recurring software, equipment purchases, staff-related payments, owner-paid costs, and bank-feed entries with unclear descriptions one category at a time. Keep personal details out of the working materials where they are not needed while retaining records that explain the business transaction.

    Checklist: test purchases and operating expenses

    Use this lane to test items bought for resale, supplies, services, recurring operating costs, and other payments incurred in carrying on the business. A familiar label does not settle tax treatment for every business or tax period, so test the evidence before assigning a conclusion.

    For each purchase or operating-cost group, answer these questions:

    • What was obtained? Record the category and the specific item or service.
    • Who was paid and when? Record the vendor, invoice number if available, amount, and payment date.
    • What proves payment? Link the business-account record, card record, or other documented payment source.
    • What explains the charge? Retain the receipt, paid bill, invoice, contract, or order record.
    • What was the business purpose? Write a concise description tied to the business activity.
    • Was there personal or shared use? Mark business-only use, mixed use, personal component identified, or use not yet confirmed.
    • What remains to verify? Record the bookkeeping account, status, and next action.

    For purchases, IRS guidance calls for records showing the payee, amount, proof of payment, date incurred, and a description of the item. Expense support similarly should show the recipient, amount, payment evidence, date, and a description of the item or service that establishes its business connection.

    Apply the same test to recurring and one-time costs, but do not combine their unanswered questions. A subscription may have a clear payment trail but an uncertain business-use percentage. A vendor invoice may describe a service but not show payment. A personal card charge may relate to the business but need a clearer record of who paid and how it was handled in the books. End each entry with one factual next step: attach support, document purpose, identify the personal component, reconcile the amount, or flag current-period eligibility for review.

    Checklist: payroll, employee benefits, and reimbursements

    Keep payroll, employer-provided benefits, and reimbursements in distinct review lanes. They may be related operational costs, but their documentation and payroll-treatment questions can differ.

    Payroll records

    • Gather payroll registers, wage and payment records, employment tax records, provider reports, and related bookkeeping entries.
    • Reconcile payroll totals to the current books and identify unexplained adjustments or owner assumptions.
    • Preserve the applicable period for every report and flag retention questions for current review.

    Employer-provided benefits

    • Identify the benefit, recipient group, period, business connection, and source records.
    • Retain records supporting the business use and note whether the matter affects employee wages or payroll reporting.
    • For a potential working-condition fringe benefit, do not presume exclusion from wages. IRS guidance describes conditions involving the employer’s business connection, whether the expense would have been an allowable employee business expense if personally paid, and substantiation of business use. Flag treatment for current professional review.

    Employee transportation and mileage reimbursements

    • Separate reimbursements from direct company-paid transportation costs.
    • For each reimbursement, gather amount, date and time, place, business purpose, and contemporaneous support such as receipts where available.
    • Retain mileage logs or other records showing the business mileage when mileage reimbursement is involved.
    • Mark accountable-plan, applicable-rate, wage-treatment, and reporting questions for current review. Do not assume a reimbursement is nontaxable based on a prior practice or a general mileage label.

    The direct action for this category is simple: assemble the payroll and reimbursement trail, then elevate unresolved treatment questions rather than making a checklist-level decision.

    Checklist: assets, equipment, and software

    Assets and software need their own schedule because a purchase record alone may not answer how the item should be treated. Keep the facts together and reserve depreciation, disposition, and current-expense decisions for applicable-period review.

    For each asset or piece of equipment, gather:

    • Description, vendor, acquisition date, cost, and payment records.
    • Invoice, receipt, financing record if relevant, and bookkeeping account.
    • Date placed into business use, location, and business-purpose description.
    • Whether the item has personal, owner, employee, or shared use.
    • Records of prior treatment, later improvements, sale, trade-in, disposal, or removal from service.

    IRS guidance says asset records are needed to verify information used to compute annual depreciation and gain or loss when assets are sold. Keep the factual record even if you are unsure whether an item is an asset, a repair, an expense, or something else for tax purposes. Flag that classification question for review.

    For software and technology resources, record the product, subscription or license period, payment amount, business function, and business-use percentage. If software has mixed personal and business use, document the business portion rather than labeling the whole amount business-only. The cited IRS guidance addresses particular conditions for some business software treatment, including use period and potential depreciation or section 179 considerations; those conditions require current-rule review before any conclusion.

    Your next action is to create an asset-and-software schedule that links each item to its source documents and identifies every mixed-use or treatment question.

    Checklist: screen home-office facts before eligibility review

    Treat a home-office item as an eligibility screen with separate factual checkpoints, not as a deduction calculation. Home use can combine business and personal activity, and applicable rules and taxpayer circumstances determine whether and how the item may be treated.

    For the space under review, record:

    • A description of the area and the activities performed there.
    • How regularly those activities occur.
    • Any personal use of the area.
    • Administrative and management activities performed there.
    • Any other fixed location where substantial administrative or management activities occur.
    • Total home floor space and floor space for the area under review.
    • Direct expenses associated with the area and indirect home expenses that may require allocation.
    • Bills, payment records, and the period covered by each cost.

    IRS guidance explains that, where the exclusive-use requirement applies, an area used for both personal and business purposes cannot be deducted as business use of home. It also describes circumstances in which a home may qualify as a principal place of business for administrative or management activities when there is no other fixed location for substantial administrative or management work.

    Keep method questions separate from space-and-use facts. The IRS describes both a regular method and a simplified option, including a cited simplified option using a prescribed rate of $5 per square foot, up to 300 square feet, for qualifying taxpayers. Do not choose or calculate a method from this checklist alone: eligibility, limits, election rules, gross-income limitations, and current-period applicability require review. The useful result is a clear record of personal use, business activities, other locations, and costs that still need professional evaluation.

    Checklist: travel, gifts, transportation, and mileage records

    Travel, gifts, transportation, and mileage deserve a separate list because they can involve heightened substantiation and time-sensitive rules. Collect the available facts first; then have the applicable-period requirements reviewed before treating an item as deductible or a reimbursement as excludable.

    For each item, retain:

    • Amount paid or reimbursed and payment evidence.
    • Date, and time where relevant.
    • Destination, place, or route where relevant.
    • Vendor, recipient, or traveler.
    • Business purpose and the business activity connected to the cost.
    • Receipt, invoice, itinerary, calendar entry, mileage log, or other contemporaneous record.
    • Whether the amount was paid directly by the business, personally by an owner or employee, or reimbursed.
    • Any policy, reimbursement report, or payroll record tied to the payment.

    IRS recordkeeping guidance specifically flags travel, gift, and transportation expenses for substantiation of certain elements when deducted. For employee transportation reimbursements, the IRS fringe-benefit guidance describes substantiation that includes amount, date and time, place, business purpose, and contemporaneous records such as receipts.

    If a log was not maintained at the time, do not recreate certainty from memory. Mark the record as incomplete support, collect what is available, and state the exact question for review: missing mileage detail, unclear business purpose, mixed personal travel, reimbursement treatment, or applicable-period documentation requirement.

    Prioritize potential deductions by evidence and rule sensitivity

    After testing each category, sort potential deductions by what must happen next rather than treating every expense as equally ready for review. This creates a decision list: entries with complete support, entries needing a missing fact or document, entries involving mixed use, and entries whose treatment depends on current rules.

    Use four priority groups:

    1. Ready to review: The category, payee, amount, period, payment evidence, source record, and business-purpose facts are available.
    2. Evidence gap: A payment or book entry exists, but a document or factual explanation is missing.
    3. Allocation question: The expense has business and personal, owner, employee, or shared use that needs to be documented and evaluated.
    4. Rule-sensitive item: The facts are available, but treatment may depend on current eligibility, payroll, reimbursement, asset, home-office, or other applicable-period rules.

    For each item, keep a short reference to the related ledger account, source documents, prior treatment if relevant, and the specific question to be reviewed. IRS guidance permits recordkeeping systems suited to the business when they clearly show income and expenses, and federal law generally does not require one special record format except in limited cases. The format should make the evidence trail and the unresolved issue easy to see.

    Review the highest-priority categories first: items with incomplete support, mixed use, unusual treatment, or a material connection to payroll, assets, reimbursements, or home use. Then compare the remaining complete entries to the books by period. This approach keeps attention on the deduction-specific facts that can change a review, instead of producing a general collection of records.

    Before sharing materials with a professional, confirm that each priority item identifies its year or current period, traces to the books, and distinguishes documented facts from owner assumptions. Include prior-year returns, payroll records, asset history, and forecasts only where they help answer the treatment question for that category.

    Choose the next verification step for each potential deduction

    The completed checklist should tell you which potential deductions can be verified next, not which expenses to claim. For every entry that is not ready to review, choose the smallest factual action that moves it forward.

    Use the status to select the action:

    • Incomplete support: Obtain the invoice, receipt, payment confirmation, or missing business-purpose detail.
    • Owner assumption: Replace the assumption with a record of the actual use, recipient, period, or payment handling.
    • Mixed use: Identify the business and personal components and preserve the facts needed for applicable-period review.
    • Current-rule question: State the category-specific issue, such as asset treatment, payroll treatment, reimbursement treatment, home-office eligibility, or a substantiation requirement.

    A useful question is tied to one expense and one missing decision fact: “What document explains this charge?” “What business use can be supported for this software?” “What facts establish the treatment question for this asset?” “What payroll review is needed for this reimbursement?” These questions keep an actual payment separate from a tax outcome.

    Where multiple records are needed to substantiate a transaction, retain the combination rather than relying on one statement or receipt. The finished checklist does not establish that an expense is deductible. It gives a credentialed professional a category-by-category record of the facts, evidence gaps, mixed-use issues, and current-rule questions for the relevant period.


    Frequently asked questions about preparing a tax deductions checklist

    What records should I gather for each potential business deduction?

    Collect the payee, amount, date or period, proof of payment, and a description of the item or service. Add the receipt, invoice, paid bill, contract, or other support that shows the business connection.

    How should I handle expenses that are partly personal and partly business?

    Mark them as mixed use and document the business-use portion separately. Do not treat the full amount as business without support for allocation and current-rule review.

    What should I do if a transaction appears in my books but the support is incomplete?

    Keep the bookkeeping entry, then flag the missing invoice, receipt, payment record, or business-purpose note. Use the item as an open question rather than filling in the gap with an assumption.

    How do I organize payroll and reimbursement items in the checklist?

    Keep them in separate lanes from ordinary operating expenses. Reconcile payroll reports, employment tax records, benefit documents, and reimbursement logs to the books, and flag wage-treatment or accountable-plan questions for review.

    What facts should I track for equipment, assets, and software?

    Record the description, cost, acquisition date, payment evidence, business-use facts, and any later sale, disposal, or mixed-use issue. For software, also note the use period and whether only part of the cost relates to the business.

    When does a home-office item need additional review?

    Any home-office entry should be checked for exclusive use, personal use, other fixed work locations, and the method used to figure the deduction. Keep the floor-space and expense records together, then let a professional review eligibility and limitations.


  • Tummy Tuck Decision Guide: What to Evaluate Before a Beverly Hills Consultation

    Tummy Tuck Decision Guide: What to Evaluate Before a Beverly Hills Consultation

    Start with the abdominal concern that needs evaluation

    A tummy tuck, also called abdominoplasty, is surgery that can remove excess abdominal skin and subcutaneous fat and may address underlying muscle laxity when appropriate. It may be part of a discussion for abdominal changes associated with major weight loss, pregnancy, or aging.

    An early step is to avoid deciding that you need a particular operation. It is identifying what you want evaluated. A lower abdomen that feels loose, a contour that seems fuller, and a persistent bulge can look similar in clothing yet involve different contributors. The consultation is where those concerns can be examined in the context of your goals, health history, and plans for the future.

    This guide can help you prepare for that conversation. It can help you organize what has changed, what you hope surgery might address, and what practical commitments you would need to consider. It cannot determine candidacy or recommend a technique for you. Those decisions require a personalized surgical assessment.

    Distinguish loose skin, abdominal fat, and possible muscle separation

    Abdominal contour is not one issue. Separating the concern you notice from the treatment you assume you need makes for a more useful consultation.

    Loose skin is one possible contributor. Abdominoplasty can remove excess abdominal skin, so this may be a central part of the discussion when skin laxity is the concern.

    Subcutaneous fat is another contributor that may be assessed. A tummy tuck can remove excess subcutaneous fat as part of the procedure, but the amount and location of abdominal fat are individual findings rather than a reason to presume the same plan will fit everyone.

    Muscle laxity or possible separation is a separate question. Diastasis recti is separation of the rectus abdominis muscles that can occur as pregnancy stretches the abdominal wall. It can vary in severity, and the separation can contribute to a persistent abdominal bulge after pregnancy. A visible bulge is not, by itself, a diagnosis; it is a reason to ask for an examination.

    This distinction matters because the operation may address underlying muscle laxity when indicated, but it is not appropriate to self-diagnose the source of a contour change. If you suspect pregnancy-related muscle separation, Cleveland Clinic describes gentle movements and work with a physical therapist experienced with diastasis recti as an approach that should be assessed for individual suitability. Bring that history to a consultation rather than assuming surgery is the only—or the right—next step.

    Understand why tummy tuck approaches and long-term limits vary

    There is no single tummy tuck plan. Published clinical guidance describes approaches that can include full abdominoplasty, mini abdominoplasty, and lipoabdominoplasty. The names alone do not tell you which approach is appropriate. The relevant question is how an approach relates to the findings from your examination, your goals, and the risks and tradeoffs that apply to you.

    A useful consultation question is: What concern would this approach address, and what would it not address? That keeps the conversation focused on a plan rather than a label. Ask how the surgeon is evaluating skin quality, abdominal fat, and muscle laxity, and why a proposed approach matches those findings.

    Timing also deserves careful attention. Weight changes can affect a tummy tuck result over time, and a tummy tuck does not prevent weight gain. If your weight is still changing, a surgeon may advise waiting; the right timing should be individualized. This is not a judgment about a number on the scale. It is a planning issue that can affect whether surgery is sensible to discuss now or later.

    Pregnancy plans, prior abdominal procedures, and the stability of your circumstances also belong in the conversation. The practical boundary is simple: do not treat a procedure name, an online image, or another person’s experience as a personal surgical recommendation. Ask for an assessment that connects your concern, timing, and options.

    Use candidacy assessment as a safety and timing checkpoint

    Candidacy is more than deciding whether you want surgery. A detailed consultation helps identify potential contraindications and modifiable risk factors. Depending on the assessment, the next step may be to defer surgery, work on factors that can be optimized, or proceed when appropriate.

    Some medical or anesthetic-risk conditions may make abdominoplasty inappropriate, which is why individualized evaluation is necessary. Published clinical guidance identifies active infection, uncontrolled disease, unstable clotting disorders, poorly controlled diabetes, pregnancy, inadequate abdominal-wall support, and certain psychological concerns among conditions that may rule out surgery. This is not a self-screening list or a diagnosis; it is a reason to share complete information with the surgeon.

    Other factors can call for particular evaluation rather than an automatic answer. Tobacco use, obesity, immunosuppression, poor nutrition, and prior abdominal surgery are examples. Conditions affecting circulation or wound healing may also increase complication risk. Smoking can raise complication risk and delay healing, so a surgeon should provide individualized cessation instructions.

    The consultation is the place to discuss whether factors such as body mass index, blood-sugar control, nutritional status, or MRSA status should be optimized before surgery. Be direct about nicotine or tobacco use, medications, medical conditions, prior operations, and recent changes in weight. The assessment may lead to a period of preparation or a decision not to proceed. That is safety-conscious planning, not a failed consultation.

    Weigh surgical risks alongside your contour goals

    A tummy tuck is surgery, and like other surgery it carries risks that should be reviewed during consultation. Potential complications include fluid collection, bleeding, wound-healing problems, infection, and contour irregularities.

    Risk information is most useful when it is tied to your individual circumstances. Rather than looking for a generic assurance, ask how your health history, prior abdominal surgery, nicotine use, and other relevant factors may shape the discussion. Ask what preparation and follow-up are expected, which concerns should prompt you to contact the care team, and what the plan is for monitoring recovery.

    A thoughtful decision holds two ideas at once: you may have a clear aesthetic or physical concern you want evaluated, and surgery can still be the wrong choice, the wrong timing, or a choice that needs more preparation. A consultation should make room for both.

    Plan the care journey and practical recovery support

    Planning and follow-up care are part of the abdominoplasty process. It is helpful to think about the experience as a sequence of decisions rather than as procedure day alone.

    First, clarify the concern and your goals. Note what has changed, when you first noticed it, whether pregnancy, weight change, or prior surgery is relevant, and what you would like a surgeon to evaluate.

    Next, complete the surgical assessment. This is where medical history, physical findings, safety considerations, and possible approaches are considered together. The assessment may lead to further preparation, a different plan, or no surgery.

    Then, plan practical support before committing. Preoperative planning can include arranging leave from work, transportation, and help during recovery, based on the surgeon’s instructions and your needs. If you care for children, animals, or another family member, include those responsibilities in the plan. Identify who can help, how you will get to and from appointments, and what responsibilities need coverage.

    Finally, plan for follow-up rather than treating it as an afterthought. Recovery needs and instructions are individualized. Do not rely on a fixed timeline from someone else’s experience. Ask the surgeon what follow-up care is anticipated and what support you should arrange so you can follow the plan you are given.

    A practical way to test whether the timing works is to list the responsibilities that normally depend on you and identify what would need to change temporarily. Consider work obligations, transportation, household tasks, childcare, pet care, and care you provide to others. For each, note whether someone can help, whether arrangements need to be made in advance, and what questions you need answered before committing to surgery. This does not replace the surgeon’s instructions; it helps you bring realistic logistics into the decision.

    It can also be useful to separate two questions that are often blended together: “Do I want my abdominal concern evaluated?” and “Can I support the care plan if surgery is recommended?” You may be ready for a consultation even if you are not ready to schedule a procedure. The consultation can clarify what preparation, follow-up, and support may be involved, while giving you time to consider whether those commitments fit your circumstances.

    Before you leave the consultation, ask what information or arrangements would be helpful to confirm next. A clear next step might be further assessment, a period of health or timing preparation, planning support at home, or additional discussion of the proposed approach and its tradeoffs. Treating those steps as part of planning can help you make a decision based on both your goals and the practical care responsibilities involved.

    Prepare questions that turn general interest into a personal plan

    A prepared consultation is not about arriving with the right answer. It is about making sure the assessment covers the questions that matter to you.

    At Dr. Golshani’s practice, the stated tummy tuck consultation reviews treatment goals and medical history and assesses skin quality, muscle laxity, and excess abdominal fat before an approach is recommended. The practice also states that the consultation covers what to expect, preparation, aftercare, likely outcome, and risks.

    Bring a written list like this:

    • Goals and limits: What specifically concerns me about my abdominal contour? What could a tummy tuck reasonably address in my situation, and what might it not address?
    • Your history: Which medical conditions, medications, prior abdominal surgeries, pregnancies, or healing concerns should affect the assessment?
    • Weight and timing: Is my weight stable enough to discuss surgery now, or should timing be reconsidered?
    • Nicotine and health factors: What must I disclose about smoking, nicotine use, circulation, wound healing, nutrition, or blood-sugar control? Are there factors that should be optimized first?
    • Procedure options: Which approach is being considered, and why? How does it relate to the skin, fat, and muscle findings from my examination?
    • Scars and tradeoffs: Where might scars be placed, what factors influence that discussion, and what contour tradeoffs should I understand before deciding?
    • Risk planning: Which risks are most relevant to me, and what preoperative and postoperative instructions are intended to address them?
    • Recovery logistics: What leave, transportation, at-home help, and caregiver arrangements should I organize based on my plan?
    • Follow-up: What follow-up care is anticipated, and whom should I contact if I have questions during recovery?

    You do not need to decide on surgery during this conversation. If the answers do not yet make the tradeoffs clear, pause and ask for clarification. The appropriate boundary is a personalized plan, not a rushed commitment.

    Take the next informed step with a personalized assessment

    Consider the decision in stages: identify the abdominal concern you want evaluated, discuss safety and timing factors openly, make sure recovery support is realistic, and understand how any proposed option relates to your own findings. General information can help you prepare, but it cannot establish candidacy or determine the right procedure.

    If you want an individualized discussion of your concerns, possible options, risks, and plan for care in Beverly Hills, a consultation can provide the clinical context this guide cannot.


    Tummy tuck consultation FAQ

    What might make a tummy tuck a poor fit for someone?

    A personalized assessment is needed, but some conditions can make surgery inappropriate or require extra caution.

    Can exercise help with diastasis recti?

    Sometimes gentle, guided movement is part of conservative care, but suitability has to be checked individually. If you think muscle separation is contributing to your bulge, it is worth asking whether physical therapy, surgery, or another approach makes sense for your situation.

    How long do tummy tuck results usually last?

    A tummy tuck does not prevent weight gain, so stable weight and realistic expectations matter when deciding on timing.

    What should I plan for before surgery?

    Plan for practical support as part of the process. That often means arranging time away from work, transportation, and help at home during recovery, along with following any preoperative instructions about smoking, health optimization, and preparation.

    What should I ask about scars and recovery at the consultation?

    Ask where scars are likely to be placed, what factors may affect their appearance, and what aftercare is expected. It also helps to ask about the main risks relevant to you, what recovery support you will need, and when follow-up visits are planned.


  • AI search optimization for healthcare: a practical operating model

    AI search optimization for healthcare: a practical operating model

    AI search optimization is SEO for AI-assisted discovery

    AI search optimization is the work of making healthcare website content easier to discover and use in traditional search and AI-assisted search experiences. In practical terms, it starts with search engine optimization (SEO): improving the visibility of website pages so they can attract more relevant traffic. The AI-search label does not replace that work. It focuses the same discipline on a search environment where a person may receive a synthesized answer, a set of links, or cited sources rather than a conventional list of results.

    You may also hear answer engine optimization (AEO) or generative engine optimization (GEO). These terms are commonly used for work intended to improve visibility in AI search experiences. For Google Search, however, Google frames generative-AI search optimization as SEO rather than a separate discipline. That is a useful operating assumption for healthcare teams: build strong search foundations and trustworthy answers before allocating time to tactics marketed as AI-specific.

    The goal is not to make a page sound like it was written for a model. The goal is to publish material that helps a prospective patient, referring organization, buyer, or partner understand a meaningful question. For a healthcare marketing team, that usually means clear explanations of services, conditions, care pathways, eligibility, locations, preparation, or organizational expertise—within appropriate editorial and organizational boundaries.

    AI SEO automation can support the operating work around research, drafting, content publishing, and updates, but it does not remove the need for accountable review. Healthcare content needs a clear owner for accuracy, source handling, and changes in organizational information. The practical question is not, “What trick earns an AI citation?” It is, “Can a search system access this page, and does the page provide a useful, reliable answer a person can evaluate?”

    That distinction also keeps expectations realistic. Optimization can improve readiness for discovery. It cannot guarantee that Google Search, ChatGPT, Perplexity, Gemini, or another experience will retrieve, summarize, link to, or cite a specific page.

    How Google and cited AI search experiences use web information

    AI-assisted search is not one uniform channel. Each experience can decide how it searches, presents information, and links to sources. That makes platform behavior important context, but a poor foundation for sweeping optimization claims.

    Google says that AI Overviews and AI Mode can surface relevant links to help people find and explore information. Google’s guidance is therefore centered on the same technical and content practices used for Search overall, rather than on a distinct publishing format for AI results.

    ChatGPT can search the web automatically based on a request or when a user chooses web search. Its web-search responses may include citations that a reader can open. OpenAI also says ChatGPT search may reformulate a prompt into one or more targeted queries for third-party search providers and may use general location information in those requests. It uses third-party search providers as well as content supplied directly by partners. A reader’s original wording, then, may not be the only wording through which a relevant page is considered.

    Perplexity’s developer documentation shows that its search-enabled Agent API can return numbered citations mapped to search-result URLs. This supports a modest but important observation: cited AI experiences may make source material visible to readers. It does not establish a universal Perplexity ranking method or a publisher playbook.

    Gemini belongs in the team’s broader monitoring landscape because audiences may use it, but this operating model does not make claims about how Gemini retrieves, surfaces, or cites publisher content. Treat unsupported platform assumptions as hypotheses to observe, not requirements to build around.

    For healthcare marketers, cited answers create a higher editorial bar. A linked page should stand on its own when a reader opens it. It should answer the page’s stated question directly, distinguish organization information from general education, and make time-sensitive claims easy to review. That is useful whether the first encounter happens through Google Search, ChatGPT, Perplexity, or a conventional referral.

    What the marketing team controls—and what search platforms control

    A durable AI search optimization program separates controllable work from platform variables. This prevents a team from treating a citation, a traffic fluctuation, or an answer format as proof that a particular tactic caused an outcome.

    The team controls:

    • Whether important pages are publicly accessible and crawlable.
    • Whether internal links help people and search systems find useful pages.
    • Whether essential information is available in readable text.
    • Whether content gives a direct, useful answer and is reviewed for accuracy.
    • Whether sources and dates are checked when the subject is accuracy-sensitive.
    • Who owns each page, what needs review, and what triggers an update.
    • Whether meaningful visitor actions are instrumented and useful qualification context reaches the CRM.

    Search platforms control:

    • Whether a page is crawled, indexed, retrieved, or served for a given search.
    • How a prompt is interpreted or reformulated.
    • Which sources are synthesized, linked, or cited.
    • How an answer appears and whether a reader clicks through.

    Google explicitly notes that even content meeting requirements, best practices, and policies is not guaranteed to be crawled, indexed, or served. That boundary should shape planning. Invest in the work that improves eligibility and usefulness, then evaluate outcomes over time without assuming a platform owes any page visibility.

    Accuracy is a second boundary. OpenAI cautions that ChatGPT search results and citations can be incomplete, outdated, or incorrect. For accuracy-sensitive information, verify the cited source, its publication or update date, and its authority. In healthcare marketing, this is a sound editorial discipline for your own pages as well: do not rely on an AI answer or a citation alone to validate a consequential statement.

    The payoff of this model is operational clarity. A marketing team can improve its inputs every month even when platform presentation changes. That is more actionable than chasing screenshots of AI answers or trying to reverse-engineer unverified ranking factors.

    Make healthcare content accessible and understandable to search systems

    Technical eligibility is not a citation tactic. It is the baseline that allows helpful content to be found and understood. Google says its generative AI search models use publicly accessible, crawlable content to learn patterns and provide relevant, grounded responses. Google also identifies clear technical structure and unique, valuable content as foundations for visibility in Google Search and its generative AI search experiences.

    Start with a focused audit of the pages that represent high-value healthcare questions. Confirm that crawling is allowed through robots.txt and through any content delivery network or hosting configuration. Confirm that important pages are reachable from relevant internal links rather than isolated in a resource library, navigation dead end, or campaign-only path. Ensure that the essential answer is available as text, not solely inside an image, video, interactive tool, or downloadable asset.

    Then review page clarity. A strong page usually has a descriptive title, a direct introduction, logical headings, and a structure that lets a reader locate the answer without scanning a wall of prose. This is not a requirement to force every page into tiny fragments. Google says there is no requirement to split content into small pieces for AI understanding and no ideal page length for generative AI search. Use the length required to answer the audience’s question well.

    Keep it aligned with visible text. Do not use markup to imply services, claims, credentials, availability, or facts that the reader cannot verify on the page itself.

    A practical audit list is:

    1. Select priority service, location, education, and conversion pages.
    2. Verify crawl access and indexation intent with the technical owner.
    3. Add or improve internal links from related high-authority pages.
    4. Move essential information into readable page text.
    5. Align structured data with visible content.
    6. Resolve outdated organizational facts before expanding the topic cluster.

    These actions support discoverability, usability, and maintenance. They do not guarantee inclusion in a particular AI answer.

    Use an evidence-led workflow for healthcare answers

    Healthcare content should be run as an editorial system, not a publishing quota. Google recommends helpful, reliable, people-first content for both Search overall and its AI features, and it emphasizes unique, valuable, expert-led material over purported AEO or GEO shortcuts. If generative AI assists creation, the resulting work must still meet Google Search Essentials and applicable Google policies.

    Use a repeatable workflow that gives each page a job:

    1. Choose a meaningful question. Start with questions that matter to the organization’s prospective audience and map them to a service, location, education need, or next step. Avoid manufacturing near-duplicate pages around every possible phrasing.
    2. Build the answer before the promotion. State the main answer early. Add the context, definitions, practical considerations, and organization-specific information needed for a reader to understand it.
    3. Verify evidence and time sensitivity. For consequential claims, retain authoritative source references, note relevant publication or update dates, and remove or revise statements that cannot be supported. This is especially important when information may change.
    4. Assign appropriate review. Route content to the subject-matter, clinical, legal, or organizational reviewer appropriate to the topic and your internal process. This is a prudent editorial framework, not clinical, legal, regulatory, or compliance advice.
    5. Name an owner and refresh trigger. Record who owns the page and what should prompt review: a changed source, revised service detail, new location information, meaningful query shift, or scheduled content audit.
    6. Publish and maintain. Content publishing is the start of the cycle. An automated content refresh process can help surface pages for review, but the team remains responsible for what stays live.

    This framework helps produce research-backed content with a visible chain of accountability. It also creates better material for downstream sales and service teams: pages are clearer about what they address, when they were reviewed, and where a prospective buyer can take the next step.

    Do not confuse a large content inventory with topical authority. The reader’s need—not a target word count or AI-search rumor—should determine the depth and format.

    Skip AI-search shortcuts that do not build durable value

    AI search uncertainty creates demand for shortcuts. Healthcare marketers should be particularly cautious because a tactic that adds little reader value can also consume review capacity that would be better spent on accuracy, clarity, and upkeep.

    For Google Search, llms.txt and similar special AI files neither help nor harm visibility or rankings, including Google’s generative AI capabilities. Maintaining those files for another system may be a separate technical decision, but it is not a Google visibility lever.

    The more serious risk is scaled, manipulative publishing. Google says that creating pages primarily to manipulate rankings or generative AI responses violates its scaled content abuse policy. This includes the temptation to generate many thin pages from related queries without adding distinct, useful information. AI SEO automation should increase editorial capacity and consistency, not multiply unsupported claims or redundant pages.

    Use this decision test before approving a tactic:

    • Does it improve the accuracy, clarity, access, or usefulness of the page for a human reader?
    • Can the team explain how it fits established technical SEO or content quality practices?
    • Does it create a review or maintenance burden that the team can sustain?
    • Is the expected benefit described as an eligibility improvement rather than a promised ranking, citation, or lead outcome?

    If the answer is no, deprioritize it. Redirect that effort toward a crawlability fix, a missing internal link, a better answer to a high-intent question, or an overdue content review. Those are controllable investments with value beyond any single AI interface.

    Connect discovery signals to qualified-lead measurement

    Visibility is an intermediate signal, not the business outcome. A useful measurement program follows the path from search discovery to meaningful engagement, qualified leads, and CRM context without claiming that an individual AI platform caused a conversion.

    Begin by defining key events that represent meaningful progress for your organization. Depending on the site and audience, these may include a completed contact request, appointment-oriented inquiry, referral-related form, resource request, demo request, or another action the team has agreed is valuable. Google Analytics attribution settings can assign credit in key-event reporting across ads, clicks, and other preceding factors. That supports a more complete view than final-click reporting alone.

    Next, build a practical measurement chain:

    • Discovery: Review Search Console performance for priority queries and landing pages. Google says AI Overview and AI Mode traffic is included in Search Console’s overall Web search reporting. Use the Generative AI performance report to monitor performance in Google’s generative AI features.
    • Engagement: Compare the landing pages attracting search visits with the actions visitors take next. Look for pages that earn attention but fail to lead readers toward a useful next step.
      Define visitor intent clearly so marketing and sales interpret it consistently.
      CRM lead enrichment should make follow-up more informed; it does not prove intent or fit on its own.
    • Assisted paths: Use assisted-conversion reporting to examine early touchpoints that engaged people but did not receive final-click credit. This is valuable for educational healthcare content, which may introduce a topic before a later branded search, direct visit, or conversion action.

    If the organization uses Google Ads, its paid and organic report can show how often website pages appeared in free organic results and which search terms were associated with those appearances. It requires the website’s Search Console account to be linked to Google Ads. Organic clicks, queries, and clicks per query can help the team assess unpaid-search visibility and engagement, but they should be read alongside landing-page quality and downstream key events.

    Do not label a lead as AI-search-sourced unless your measurement setup can support that attribution. Instead, assess whether the overall program is improving the quality of search discovery, content engagement, qualified-lead signals, and CRM follow-up context.

    Start with a repeatable optimization cycle

    A first operating cycle does not need a large platform-specific experiment. It needs disciplined execution on the work the team can verify.

    1. Audit crawlability, internal links, text availability, and structured-data alignment for priority pages.
    2. Select a small set of high-value healthcare questions tied to real audience and business needs.
    3. Publish clear, reviewed, research-backed content with accountable ownership.
    4. Set refresh triggers for changing sources, organizational facts, and underperforming priority pages.
    5. Configure meaningful key events and a CRM handoff that preserves useful qualification context.
    6. Review Search Console discovery signals, landing-page behavior, and assisted-conversion paths before expanding the program.

    This sequence connects technical SEO, trustworthy content publishing, automated content refresh support, visitor intent, and CRM measurement into one manageable program. It also keeps the team honest about uncertainty: Google does not guarantee crawling, indexing, or serving even for well-optimized pages, and other AI search experiences control their own retrieval and citation choices.

    A practical next step is to make priority content easier to access, easier to understand, and easier to maintain—then measure discovery, engagement, and sales-context signals over time.

    Frequently asked questions about AI search optimization for healthcare

    Is AI search optimization different from SEO for Google Search?

    Usually it is treated as the same foundation. The practical work is still technical SEO and helpful, reliable content, with extra attention to how AI-assisted search experiences may surface or cite pages.

    How should a healthcare team measure whether AI search visibility is helping lead generation?

    Measure the full path from discovery to key events, assisted conversions, and CRM context. Search Console, Google Analytics attribution, and qualified-lead tracking are more useful than trying to attribute every visit to one AI platform.

    Do special files like llms.txt improve visibility in Google Search?

    No. Google says those files do not help or harm visibility or rankings in Search. Effort is better spent on crawlability, internal links, and clear page content.

    What content changes tend to help AI-assisted search experiences find a page?

    Pages that are publicly crawlable, text-based, clearly structured, and aligned with visible structured data are easier to discover. Content also needs a direct answer, useful context, and regular review when information changes.

    Can a healthcare team rely on AI-generated content for this work?

    AI can support drafting and content publishing, but the final page still needs accountable review and source checks. For healthcare topics, that review should be especially careful when claims may affect trust or decision-making.

    Should teams expect the same visibility behavior across ChatGPT, Perplexity, and Gemini?

    No. It is safer to optimize for strong search foundations and verify each platform’s current behavior before drawing conclusions.

  • Small-Business Tax Planning Packet Checklist for Austin Owners

    Small-Business Tax Planning Packet Checklist for Austin Owners

    Build a review-ready packet before drawing tax conclusions

    A useful tax-planning meeting starts with an organized record packet, not a list of assumed deductions or tax-saving ideas. Your goal is to make the current facts visible: what the books show, what documents support them, what you are forecasting, what is absent, and what needs professional judgment.

    For an Austin small-business owner, that packet can bring together current bookkeeping, prior-year returns, payment records, payroll and owner-compensation materials, contractor information, asset activity, and dated forecasts. It is preparation for a conversation with a credentialed tax professional—not a way to decide tax treatment, eligibility, entity choices, deductions, credits, or filing outcomes on your own.

    The IRS says good records are needed to prepare returns and support reported income, expenses, and credits. A packet that preserves both the evidence and the uncertainty gives a professional a clearer starting point than a folder of unlabeled documents.

    Label every packet item by its evidence status

    Use one status on every report, document group, forecast, and question. The labels are simple, but they prevent an estimate from being mistaken for a record or an unanswered question from being treated as a conclusion.

    Status Use it when What belongs in the packet Reader action
    Confirmed record A document or reconciled report supports the item for a stated period. The source document, report location, period, and a short note. Keep the evidence with the related book entry or question.
    Owner assumption or forecast The item reflects an expectation, estimate, or management view rather than completed activity. The assumption, date prepared, period covered, and basis you used. Label it as an assumption; do not present it as a completed transaction.
    Missing information A needed document, amount, account detail, or period is unavailable. A description of what is absent and where you looked. Identify the person, system, or statement needed to fill the gap.
    Credentialed-professional review required The issue depends on current rules or tax treatment. The facts, records, period, and precise question. Bring it for current-period review rather than deciding applicability yourself.

    Apply the label at the smallest useful level. A monthly bank statement may be a confirmed record while several transactions within that month remain missing information. A forecast may be well documented but still remain an owner assumption. The point is not to make every item look complete; it is to let the reviewer see exactly what can be relied on and what needs follow-up.

    Checklist: current bookkeeping and transaction support

    Start with the period you want reviewed. Create one folder or clearly named digital location for each year and, within it, separate current-period materials from prior-year records. The IRS says a business may choose a recordkeeping system suited to its operations that clearly shows income and expenses, subject to limited exceptions. It also says a recordkeeping system should include a summary of business transactions, and that business books must show gross income, deductions, and credits.

    Gather these current-bookkeeping items:

    • Current profit-and-loss report, balance sheet, general ledger, or other transaction summary used by the business.
    • Business bank-account statements for the period, plus credit-card or payment-account statements used for business transactions.
    • Reconciliation reports or a note identifying which accounts and months are reconciled, unreconciled, or not yet entered.
    • Sales reports, invoices, receipt books, deposit records, payment-processor reports, and other support for money received.
    • Paid bills, vendor invoices, receipts, canceled checks, and proof of electronic payment for money spent.
    • A short explanation of any personal account, cash activity, loan activity, or payment platform that appears in the business records.
    • A list of bookkeeping changes during the period, such as a new system, new account, changed chart of accounts, or revised reporting process.

    Sales slips, paid bills, invoices, receipts, deposit slips, and canceled checks are among the supporting documents the IRS lists. Those documents support entries in the books and on a tax return. Organize them by year and by type of income or expense so a reviewer can move from a report line to underlying support without guessing.

    Electronic files are workable when they are orderly. The IRS says electronic systems are subject to the same basic recordkeeping principles and requirements as hard-copy records. Give files a consistent name that includes the period and document type, such as 2026-03 business checking statement or 2026 Q1 vendor invoices. Mark the folder or report confirmed record only if you can identify the period and supporting source. Otherwise, use the appropriate uncertainty label.

    Checklist: income, payments, purchases, and expense evidence

    Treat the books as a summary and the underlying records as the support behind that summary. This is especially important when a transaction is unusual, large for the business, split across accounts, or not clearly described.

    For income and gross receipts, gather:

    • Customer invoices, sales summaries, receipt records, and payment-processor reports.
    • Deposit information that connects receipts to a bank or other account.
    • A list of items that do not clearly match between sales records and deposits.
    • Notes identifying the source of each unusual receipt or nonroutine payment.

    IRS guidance says gross-receipt support should show the amount and source of business receipts. Do not infer a source from a bank description if you cannot confirm it; mark the entry missing information or credentialed-professional review required, depending on the question.

    For purchases and expenses, gather:

    • Vendor invoices, receipts, paid bills, account statements, canceled checks, card statements, and electronic-payment confirmations.
    • A transaction note where the document does not plainly show what was purchased or what service was received.
    • Any correspondence or agreement that helps explain an unusual payment.
    • A list of transactions for which payment evidence exists but the invoice, receipt, or business-purpose description is absent.

    For purchases, the IRS lists the payee, amount paid, proof of payment, date incurred, and a purchase description among the identifying information supporting records should show. For expenses, it similarly lists the payee, amount paid, proof of payment, date incurred, and a description showing business purpose. More than one document may be needed to substantiate all elements of a purchase or expense.

    A practical packet note can be brief: March vendor payment — confirmed payment record; invoice missing; business-purpose description needed. That phrasing documents what you know without converting an incomplete file into a tax conclusion. If a payment may involve a deduction, credit, owner transaction, related party, travel, gift, transportation, or other tax-sensitive treatment, place the item in the professional-review category.

    Checklist: prior returns, payroll, assets, contractors, and forecasts

    Complete the packet with records that provide context for the current period. Keep each category separate, identify the applicable period, and avoid deciding whether an item qualifies for a particular tax result.

    Prior-year returns and carry-forward context

    • Copies of filed business and owner returns that relate to the business.
    • Prior-year financial statements, workpapers you have, and notices or correspondence you want reviewed.
    • A list of changes since the prior year: ownership, operations, locations, financing, payment methods, payroll, or major purchases.

    The IRS advises keeping copies of filed returns because they can help with future returns and amended-return computations. Label prior filings as confirmed record; label any interpretation of what they mean for the current period as credentialed-professional review required.

    Payroll and owner-compensation materials

    • Payroll registers and payroll-provider reports.
    • Wage-payment dates and amounts, tax-deposit confirmations, filed payroll-return copies, and employee information maintained for payroll purposes.
    • Withholding certificates, benefit or reimbursement records, and support for any payroll-related item you want reviewed.
    • Owner-payment and owner-draw records, clearly separated from employee payroll records.

    The IRS lists payroll payment records, employee information, withholding certificates, deposit records, filed returns, and substantiation for certain benefits, reimbursements, and credits among employment-tax records. Questions about worker treatment, owner compensation, payroll treatment, benefits, reimbursements, or credits require credentialed-professional review.

    Contractor information

    • Agreements, invoices, payment history, and contact records for contractors.
    • A list of payments lacking an invoice, agreement, or clear description of services.
    • Any question about the proper treatment of a worker or payment.

    Keep the facts and the question together. Do not use the packet to reach a contractor, payroll, or reporting conclusion.

    Asset activity

    • Purchase documents, invoices, proof of payment, financing records, and descriptions for business property acquired during the period.
    • Records of property sold, disposed of, transferred, or no longer used in the business.
    • Existing asset schedules, if available, and notes on missing asset details.

    The IRS says businesses need asset records to verify asset information and to calculate annual depreciation and gain or loss when assets are sold. Whether a particular item receives a particular treatment is a professional-review question.

    Dated forecasts

    • A cash, revenue, staffing, purchase, financing, or expansion forecast relevant to the planning discussion.
    • The preparation date, covered period, major assumptions, and source of the underlying figures.

    Forecasts are useful planning inputs, but they are not transaction records. Label them owner assumption or forecast and identify changes that would materially alter the forecast.

    Checklist: catch up incomplete current-period bookkeeping without guessing

    Incomplete books do not prevent you from preparing for review. They do change the job: assemble the available evidence, make the gaps visible, and avoid filling those gaps with unsupported conclusions.

    Use this sequence for the catch-up period:

    1. Define the period. Write down the first and last month that need attention. List every account, payment platform, and record location used during that period.
    2. Assemble source documents. Pull statements, invoices, receipts, deposit records, card records, paid bills, payroll reports, and sales reports. Keep originals or accessible copies with the reconstruction file.
    3. Organize transactions by month. Group the documents and available entries by month before trying to categorize disputed items. The goal is an orderly chronology, not a final tax classification.
    4. Reconcile available accounts to statements. Identify which months and accounts match the available statements and which do not. For most small businesses, the IRS says the business checking account is the main source for entries in business books; it is often a useful starting point, not proof that it captures every business fact.
    5. Compare reports with filed returns. Put current or reconstructed reports beside relevant filed-return copies and note differences, missing periods, and unexplained balances. Do not change a conclusion simply to make documents appear consistent.
    6. Label each discrepancy. Use confirmed record where support is present, missing information where documents are absent, and credentialed-professional review required where the issue depends on treatment or current rules.
    7. Prepare a reconstruction file. Include the transaction list, source documents, reconciliation notes, assumptions, and unresolved questions in one location for review.

    IRS material states that partial records can serve as a basis for reconstruction using a sound and reasonable estimate when formal books and supporting documents are unavailable. It also says a knowledgeable preparer can guide reconstruction from partial records and may refuse preparation if the reconstructed records are not sufficiently accurate. That is the boundary: bring partial records and clear gap notes forward; do not manufacture support or force a conclusion from incomplete information.

    Log each unresolved question with its records, period, status, and next action

    A question log turns uncertainty into an agenda. Use one line per issue, even when several issues concern the same vendor, account, or forecast. Keep the wording factual and specific enough that a reviewer can see what materials relate to the question.

    Question Relevant period Supporting records Status Next action
    What is the appropriate treatment of this payment? Month, quarter, or year Invoice, payment proof, account entry, agreement Credentialed-professional review required Provide complete file for current-period review
    Why does this deposit not match the sales report? Stated month Deposit record, sales report, payment-processor detail Missing information Obtain missing processor report or customer record
    Is this forecast assumption still reasonable for planning? Forecast period Forecast version, assumptions, management notes Owner assumption or forecast Update assumption date and bring for discussion
    Is the ledger entry supported? Stated month Receipt, invoice, bank statement, reconciliation note Confirmed record or missing information Retain support or identify the missing document

    Add a short identifier to each question, such as Q-01, so the reviewer can refer to it without searching through attachments. A good entry names the issue without presuming the answer. For example, write Question about treatment of equipment purchase rather than depreciation deduction approved.

    Before the meeting, sort the log by period and then by status. Start the conversation with items requiring professional review and missing information that could materially affect the records. End every row with a direct next action: provide a document, update a forecast, reconcile a report, or obtain credentialed review.

    Mark current-rule and tax-treatment issues for credentialed review

    The packet should document facts; it should not decide whether current law applies to those facts. Use credentialed-professional review required for entity-specific, transaction-specific, payroll, contractor, credit, deduction, depreciation, multistate, Texas filing, or retention questions.

    Escalate when you need a current answer about:

    • Entity, ownership, or owner-payment treatment.
    • A worker, contractor, payroll, benefit, reimbursement, or compensation issue.
    • A credit, deduction, depreciation, asset disposition, financing, or unusual transaction.
    • Travel, gift, or transportation expenses. The IRS states that deductible travel, gift, and transportation expenses are subject to specific substantiation requirements; current requirements should be reviewed before reliance.
    • Texas or multistate filing, registration, tax, or reporting matters.
    • How long to retain a particular record. IRS guidance generally says to keep records supporting income, deductions, or credits until the applicable return’s limitations period expires, and property records generally through the limitations period for the year of disposition; confirm current requirements before relying on a retention decision.
    • Employment-tax retention. The IRS says to retain employment-tax records for at least four years after filing the fourth-quarter return for the year; confirm current requirements before reliance.

    Write the issue as a question, attach the relevant records, state the period, and stop there. A clearly labeled unresolved item is more useful than an unsupported answer.

    Use the completed packet to focus the next conversation

    Before handing off the packet, do one final pass: confirm the period on each folder, ensure each item has a status label, attach or locate the source records for confirmed items, and place every open issue in the question log. Your packet does not need to be flawless to be useful. It needs to show what is documented, what is assumed, what is missing, and what needs current professional judgment.

    Bring a partially completed packet forward when the remaining uncertainty is visible. That allows the next conversation to focus on records, assumptions, forecasts, and unresolved questions instead of reconstructing the basic file from scratch.


    Frequently asked questions about preparing a tax-planning packet

    What should be included in a small-business tax-planning packet?

    Include current bookkeeping reports, bank and card statements, source documents for income and expenses, prior-year returns, payroll records, asset records, and any dated forecasts you plan to discuss. Keep each item tied to its period and source so the reviewer can trace it quickly.

    How should I label items when I am not sure they are complete?

    Use one of four labels: confirmed record, owner assumption or forecast, missing information, or credentialed-professional review required. That makes it clear what is supported, what is estimated, what is absent, and what needs current tax judgment.

    What if my current bookkeeping is incomplete before the review?

    Gather the available source documents, organize them by month, reconcile what you can to statements, and list the gaps instead of guessing. Partial records can still help build a reasonable reconstruction, but unresolved items should stay labeled as missing or needing professional review.

    Which documents are most useful for income and expense support?

    Bank and payment records, invoices, receipts, paid bills, deposit slips, canceled checks, and account statements are all useful. For each transaction, keep the payee, amount, proof of payment, date, and a short business-purpose description when available.

    Do I need to keep prior-year returns in the packet?

    Yes. Copies of filed returns can help with future return preparation and amended-return computations, and they also give context for changes from one year to the next. Keep them with any notes about what changed since the prior period.

    When should a question be marked for professional review?

    Mark it that way when the answer depends on current tax treatment or a specific rule, such as payroll, contractor, entity, credit, deduction, depreciation, retention, or asset-disposition questions. Attach the related records and state the period, then let the reviewer make the call.

    How should I handle asset, payroll, and contractor records?

    Keep asset purchase and disposition documents, payroll registers and deposit confirmations, and contractor agreements or invoices in separate sections with clear periods. These records often affect different tax questions, so separating them helps the reviewer see which items are confirmed and which still need follow-up.


  • Business Process Automation: How to Assess One Workflow Before You Automate

    Business Process Automation: How to Assess One Workflow Before You Automate

    Business process automation is a workflow-design decision, not simply a tool choice

    Business process automation (BPA) is can be approached as a decision about how work should move, who may act, and what happens when the normal path breaks—not as a search for a tool that can mimic every manual step.

    Workflow automation can be described as designing repeatable work to progress through clear rules, triggers, and conditions. A trigger may create a task, assign an owner, request an approval, or send an update. That makes it useful for coordinating a known process: an event occurs, required information is present, and the next permitted action is defined.

    Related terms matter because they imply different operating boundaries. IBM describes robotic process automation (RPA) as technology for repetitive office tasks such as extracting data, filling forms, and moving files. RPA may use APIs or user-interface interactions across separate systems. It is not synonymous with AI. IBM distinguishes RPA from AI capabilities such as machine learning, natural-language processing, reasoning, hypothesis generation, and analysis. IBM also describes intelligent automation as an expansion of RPA that incorporates AI subdisciplines including ML, NLP, and computer vision.

    For an operations leader, the practical distinction is straightforward. Use deterministic workflow automation where the inputs, rules, and allowed output can be stated clearly. Consider an AI-enabled step only where some bounded interpretation of unstructured material is genuinely needed. Keep a person responsible where the work requires material judgment or authorization. The point is not to classify a platform; it is to define a clear, workable boundary for each part of the process.

    Decide whether the workflow is ready to assess before trying to automate it

    Repetition alone is not a sufficient reason to automate. A repetitive task can still be unclear, frequently changing, or too marginal to justify the effort of defining and maintaining an automated path. A candidate-screening approach considers repetition, manual cost, stability, and meaningful business impact. It also cautions that some processes need clarification, simplification, or standardization first—and that some are rationally left manual.

    Treat the following as an editorial screening checklist, not a promise of implementation value:

    • Is there a recognizable trigger? The team should be able to say what starts the work and what information must be available at that point.
    • Is the normal path stable enough to describe? If people routinely improvise the steps, resolve the same issue in incompatible ways, or use undocumented workarounds, map and simplify before automating.
    • Are decisions rule-based or judgment-based? A rule such as “route incomplete submissions for review” is easier to bound than a decision requiring an open-ended assessment of significance.
    • Are exceptions visible? Work that looks simple in the happy path can be dominated by edge cases. Identify them before selecting technology.
    • Is there an accountable owner? Automation does not remove the need for a person or team to own the workflow, its changes, and its unresolved cases.
    • Would a defined boundary be useful even if no automation follows? If mapping exposes duplicated entry, unclear approvals, or a missing handoff, that is useful operational learning—not a failed automation project.

    The selected source warns that automating too early can hard-code a messy process, making it more opaque, brittle, and harder to evolve. That is a useful warning, especially when a team is tempted to start with the most frustrating manual process. Start instead with a workflow segment that is sufficiently understood to test the discipline of mapping, ownership, exceptions, and controls.

    Map triggers, steps, decisions, exceptions, handoffs, and owners before choosing automation

    A process map is a visual representation of work from its initial trigger to its final outcome. It can show steps, decisions, inputs, outputs, and roles. Used well, mapping can surface bottlenecks, redundancies, handoffs, control points, and potential root causes of errors or rework.

    Do not settle for a sequence of boxes labeled “receive,” “review,” and “complete.” For each segment, ask:

    1. What event starts this segment?
    2. What inputs are required, and where do they come from?
    3. What rule, decision, or judgment determines the next step?
    4. What action is permitted after that decision?
    5. What exception stops or redirects the normal path?
    6. Who owns the segment and the exception queue?
    7. What approval, if any, is a condition of moving forward?
    8. What systems or data sources does the segment depend on?

    Clearpath describes its Boundary Map as an initial scoping framework that approaches automation one workflow segment at a time. According to Clearpath, each segment records its trigger, required inputs, deterministic rules, judgment point, permitted action, exception or escalation path, and accountable owner.

    Its value is practical: it prevents a vague statement such as “automate invoice handling” from hiding several different kinds of work. Intake, validation, exception interpretation, approval, and payment execution may belong to one business workflow, but they need not have the same automation disposition or the same authority boundary.

    Set the boundary between deterministic automation, agent assistance, and human decision

    A useful assessment assigns a primary disposition to each segment rather than treating the full workflow as entirely manual or entirely automated. Clearpath’s framework uses three dispositions: deterministic automation, agent assistance, and human decision.

    Deterministic automation fits work where inputs, rules, and the permitted action are fully defined. For example, a segment may compare fields against fixed criteria, create a record, or route a case according to an explicit rule. The key test is not whether the task is simple; it is whether the organization can state what the system is allowed to do for the defined inputs.

    Agent assistance fits a narrower situation: unstructured input needs bounded interpretation, while permissions and output remain fixed. The word “bounded” does important work. The system should have a constrained job, a defined output shape, and no implied authority to expand its own scope. An interpreted document field, a classification suggestion, or a draft route may be useful inputs to the next step; they should not automatically become permission to take an unrelated consequential action.

    Human decision fits segments where material judgment or authorization must remain with a person. This is not an admission that automation has failed. It is a design choice that makes the boundary explicit. A workflow can automate intake, validation, record creation, reminders, and routing while reserving approval or exception resolution for an accountable decision-maker.

    This framework is Clearpath’s stated method, not a universal standard. Still, the underlying editorial principle is broadly useful: choose the narrowest automation authority that can perform the defined work. A more capable technology does not remove the need to define what it may do.

    Treat permissions, controls, and exception paths as part of the workflow design

    Automation does not eliminate operational risk; it can move risk into data paths, permissions, workflow logic, model behavior, integrations, logs, and exception handling. That means controls and exception paths are part of the workflow design, not post-launch documentation.

    At scoping stage, ask what access the segment truly needs. Separate the ability to read information, prepare an output, route work, approve a decision, and execute an action. Within Clearpath’s scoping framework, document the permissions a segment needs rather than leaving its workflow boundary undefined. Also identify the input contract: what fields or documents are expected, what makes them incomplete, and what should happen when validation fails.

    Clearpath says its control envelope records permissions; input and output contracts; validation; approval; logging; uncertainty handling; reversibility; and execution controls around a segment’s primary disposition. It also says an assessment records dependent systems and data sources, plus unresolved integration contracts, before production start. These are useful scoping categories, but they are not a complete security, legal, regulatory, or production-control standard.

    Exception design deserves equal attention to the normal path. Define which cases are rejected, held, routed for review, or escalated; who receives them; and what information accompanies the handoff. Define how changes to rules, source systems, and workflow ownership will be reviewed. If a workflow’s stop conditions and escalation path remain unclear, record them as unresolved scoping questions.

    For AI-enabled segments, avoid false certainty. OWASP states that its Q1 2026 GenAI exploit round-up covers January 1 through April 11, 2026 and is not exhaustive. The narrow takeaway is not that every AI-assisted workflow is unsafe; it is that an AI feature should not be treated as a reason to relax workflow boundaries, validation, authorization, or exception handling.

    Walk through a hypothetical invoice-exception workflow segment by segment

    The following example is hypothetical and illustrative only. It is not a customer case study and does not represent an outcome claim.

    Segment 1: validation. The segment begins when an invoice and purchase order are available. It reads those documents and a fixed tolerance, applies exact comparison rules, and routes a mismatch to exception review. This is a plausible deterministic segment because the trigger, inputs, comparison rule, and next action are defined. Its boundary should still state what happens when a document is unreadable, an expected field is absent, or the source data conflicts.

    Segment 2: exception handling. After a mismatch, the exception segment begins with a written reason. In this hypothetical design, it uses read-only invoice access, a fixed route taxonomy, and a fixed output schema. Outputs are validated and logged; unmatched values are escalated. Crucially, the segment has no payment permission and remains owned by the accounts-payable exception owner. If bounded interpretation is used to sort or summarize an exception, the interpretation assists the route; it does not authorize payment.

    Segment 3: payment. Payment begins only after exception resolution and an approved payment instruction. Finance retains authorization. Deterministic finance controls execute only after that approval, while rejected or incomplete instructions are placed on hold.

    The example illustrates why “automate invoice exceptions” is too broad a requirement. The validation segment may be deterministic. The exception segment may need constrained assistance or human review. The payment segment can remain conditional on a finance authorization. Mapping these separately makes authority, ownership, and escalation visible before anyone assumes that a single automation mode should govern the entire workflow.

    Compare automation options by asking whether they can represent the workflow boundary

    Vendor comparison should begin with your workflow boundary, not a feature checklist detached from the work.

    Ask each option:

    • Can it represent a specific trigger, required inputs, explicit rules, permitted actions, and accountable owner for each segment?
    • Can the team distinguish deterministic execution from a bounded interpretation step and from a human decision?
    • Can permissions be limited to the action required by the segment, rather than granted broadly across the workflow?
    • Can approval checkpoints be represented where authorization must remain human?
    • Can incomplete, invalid, uncertain, or unmatched inputs follow a defined hold, review, or escalation path?
    • Can the workflow validate required inputs and outputs before proceeding?
    • Can the team review a record of workflow steps and tool actions appropriate to its operating needs?
    • Can owners understand and change the workflow logic without losing track of its exceptions and dependencies?
    • Can dependent systems, data sources, and unresolved integration contracts be documented before production decisions?
    • Can the design accommodate change—new source fields, altered policies, revised routing rules, or a new accountable owner—without silently expanding authority?

    Clearpath states that its product can enforce owner-configured approval checkpoints and retain a run record of workflow steps and tool actions. Those are first-party product statements, not a claim that they satisfy every organization’s control requirements. The evaluation task remains the same: verify whether a prospective option can represent the boundaries your workflow actually needs, and determine what additional technical, security, governance, or operational review is required.

    FAQ: Practical questions to resolve before assessing a workflow

    What makes a workflow a good candidate for business process automation?

    A good candidate is usually repeatable, stable enough to describe, and important enough that manual effort matters. It should have a clear trigger, visible exceptions, and an accountable owner. If the process is still unclear or inconsistent, it may need simplification or standardization first.

    How is business process automation different from RPA and AI?

    Business process automation is the broader design of how work moves through rules, handoffs, and approvals. RPA is one way to automate repetitive office tasks. AI-enabled automation adds bounded interpretation for unstructured input, but it should not be treated as the same thing as deterministic automation.

    What should a process map include before you automate anything?

    A process map should show the trigger, inputs, steps, decisions, outputs, roles, handoffs, approvals, and exception paths. It should also identify bottlenecks, redundancies, control points, and the systems or data sources the workflow depends on.

    When should a human stay in the loop instead of automating a step?

    A human should stay responsible when the step requires material judgment or authorization. Automation can still handle intake, validation, routing, and logging, but the final decision should remain with a person when the boundary is not fully rule-based.

    What risks should operations teams check before moving a workflow into production?

    Check where risk shifts once automation is added: data paths, permissions, workflow logic, integrations, logs, exceptions, and any AI behavior used in the process. Also confirm access boundaries, approval checkpoints, validation rules, and who owns unresolved cases and change requests.

    How should I compare automation options for a specific workflow?

    Compare options against the workflow boundary, not just features. Ask whether the system can represent triggers, required inputs, explicit rules, permitted actions, approvals, exception handling, and accountable ownership for each segment of the process.

    Bring one workflow to an assessment and identify its unresolved controls


  • Is This Manual Workflow Ready for Business Process Automation? A Segment-by-Segment Decision Guide

    Is This Manual Workflow Ready for Business Process Automation? A Segment-by-Segment Decision Guide

    Decide on the workflow before deciding on automation

    A manual workflow is not automatically an automation opportunity. The useful first question is narrower: which part of this workflow is defined enough to be handled differently, and where must people retain control?

    Business process automation (BPA) uses technology to streamline repeatable tasks and reduce manual effort in enterprise workflows. It can cover a simple function such as an invoice approval or a process that crosses departments. That breadth is why BPA should not be treated as a single technology purchase.

    Workflow automation is the more concrete operating layer: Clearpath defines it as using software to carry out defined manual workflow steps. AI-assisted automation adds another possibility: software may interpret unstructured material, such as a document or message, before a workflow moves forward. Interpretation is not the same as authority, however. A system can help classify or summarize information without being allowed to approve, pay, change records, or communicate externally.

    Start with one workflow, not an aspiration to automate everything. The aim is to make a defensible scoping decision: automate fully defined work deterministically; consider bounded AI assistance only where interpretation is needed and authority can remain fixed; retain human decision-making where material judgment or authorization is involved. This approach also avoids over-automation, which can make work rigid when people need flexibility and judgment.

    Map how the work actually moves from trigger to outcome

    Before designing a future state, map the current state. Workflow mapping documents how work moves from start to finish: tasks, decisions, handoffs, systems, and people. It is evidence gathering, not a promise that the present process is worth preserving.

    For one candidate workflow, capture:

    • Trigger: What event starts the work?
    • Outcome: What counts as complete, and who recognizes completion?
    • Steps and handoffs: What happens, in what order, and where does work wait?
    • Inputs: Which fields, documents, messages, or records are required?
    • Rules and decisions: Which choices follow stated rules, and which depend on context or judgment?
    • Systems and data: Where is information read, written, or reconciled?
    • Exceptions: What causes the normal path to stop, retry, escalate, or branch?
    • Controls and ownership: Who may approve, override, release, or correct the result?

    Mapping and workflow design are related but distinct. Mapping shows how work currently travels across roles, applications, decisions, controls, and handoffs. Design decides how the work should be structured and governed to serve an intended outcome. Keep those activities separate long enough to expose informal workarounds, unclear ownership, and hidden exceptions.

    Test automation viability one bounded segment at a time

    A whole workflow often contains several different kinds of work. Treating it as all-or-nothing obscures that reality. Clearpath’s Boundary Map is an initial scoping tool for examining one workflow segment at a time. For every segment, record:

    1. Trigger — the event that permits the segment to begin.
    2. Required inputs — the information and source records it needs.
    3. Deterministic rules — the conditions that can be stated and tested.
    4. Judgment point — where context, interpretation, or discretion enters.
    5. Permitted action — exactly what the segment may do.
    6. Exception or escalation path — what happens when inputs, rules, or confidence are insufficient.
    7. Accountable owner — the person or role responsible for the segment’s outcome.

    The test is not whether every field can be filled in immediately. Missing answers are valuable findings. If no one can identify the authoritative input, explain the rule, define a permitted action, or own an exception, the segment is not yet ready for unattended execution. It may still be worth improving, but the immediate output should be an unresolved design question—not a claim of automation suitability.

    The Boundary Map is not a complete production-control specification. It is a way to establish the boundaries that production design must later honor.

    Screen for work that is defined and stable enough to automate

    A promising automation segment usually has a stable trigger, known inputs, explicit rules, a bounded action, and a workable exception path. Use the following screen as a conversation guide rather than a scoring formula.

    Repeatability. Does the segment recur in a recognizable pattern? Repetition alone is insufficient, but a one-off activity with constantly changing circumstances is a weak starting point.

    Input quality. Are required inputs present, accessible, and sufficiently consistent? Structured data can support deterministic rules. Unstructured material may still be usable, but it introduces interpretation and uncertainty that must be handled explicitly.

    Rule clarity. Can the normal decision be expressed as conditions that a team can review and test? If experienced staff say “it depends,” ask what it depends on. The answer may reveal a rule, a missing data source, or a genuinely human judgment.

    Exception behavior. Are exceptions known, categorized, and routed to an owner? An automation that cannot safely stop is not mature merely because the happy path is clear.

    System dependencies. Can the required systems and data sources support the proposed interaction? Record dependencies and unresolved integration contracts instead of assuming that access or data transfer will be available.

    Action boundary. Is the proposed action reversible, limited, and appropriate to the certainty of the inputs? A segment that drafts a recommendation has a different boundary from one that changes a record or releases a payment.

    Ownership. Is there an accountable owner for rules, exceptions, approvals, and change requests? Technology cannot resolve a decision-rights gap.

    Complex, frequently changing workflows and unstructured tasks may not fit robotic process automation alone. Depending on the work, possible approaches include a business-process-management approach, AI-supported interpretation, or human-in-the-loop handling. That is not a reason to add AI by default; it is a reason to match the operating model to the uncertainty in the work.

    Assign deterministic automation, bounded AI assistance, or human decision

    After mapping a segment, assign a provisional disposition. Clearpath’s three-disposition model makes the trade-off explicit.

    1. Deterministic automation fits when inputs, rules, and the permitted action are fully defined. The system follows specified logic: if stated conditions are met, it performs a stated action; otherwise it follows an exception route. This is the clearest fit for repeatable validation, routing, status updates, or other bounded steps. The practical question is whether the organization can specify and maintain the rule—not whether the step looks routine from a distance.

    2. Bounded AI assistance fits when unstructured input needs interpretation but permissions and outputs remain fixed. For example, an AI-enabled component might extract candidate information, classify a request, or prepare a structured handoff for review. The boundary matters: the component should have defined inputs, a limited output format, a fixed set of permitted actions, and a route for uncertainty. It should not silently convert an interpretation into unrestricted operational authority.

    3. Human decision fits when material judgment or authorization must remain with a person. This may include decisions with significant consequences, ambiguous cases, competing priorities, or approvals where the accountable person must exercise discretion. Human review is not a failure of automation; it is often the correct control boundary.

    One workflow can contain all three dispositions. A sound design does not seek maximum automation. It seeks the smallest authority appropriate for each segment, while keeping exceptions visible and ownership clear.

    Keep AI interpretation within explicit authority boundaries

    AI-enabled workflow steps require a separate authority conversation. An LLM-based system may be given tools or extensions that let it call functions or interact with other systems. That connection can be useful, but it changes the risk profile from “generate text” to “take action.”

    OWASP describes excessive agency as a vulnerability in which unexpected, ambiguous, or manipulated LLM outputs can enable damaging actions. It identifies excessive functionality, excessive permissions, and excessive autonomy as contributors. Its AI-agent guidance also highlights risks including prompt injection, tool abuse and privilege escalation, sensitive-data exposure, high-impact action abuse, and approval manipulation.

    For an operations leader, the practical conclusion is not that AI assistance is categorically unsuitable. It is that an AI-assisted segment needs an explicit authority boundary before it receives tools or access:

    • limit the systems and functions available to the segment;
    • grant only the permissions needed for its permitted action;
    • define input and output contracts rather than accepting unrestricted content;
    • validate outputs before consequential downstream use;
    • send uncertain, ambiguous, or policy-sensitive cases to a named human owner;
    • require independent human approval for consequential actions when the organization determines that approval is needed;
    • preserve records that allow the team to reconstruct what happened; and
    • define how an action can be stopped, corrected, or reversed where feasible.

    These are design considerations, not a declaration that any workflow is secure or compliant. Actual access, data handling, approval authority, and control requirements depend on the organization and workflow.

    Turn the workflow scope into implementation and governance controls

    A viable scope is the beginning of implementation, not its end. BPA implementation may require workflow redesign, system integration, and staff training. Plan the operating changes alongside the technology work.

    For each approved segment, turn the map into implementation questions: Which systems and data sources does it depend on? Is an integration contract unresolved? Who configures and reviews permissions? What validation occurs before an action? Which approval checkpoints apply? How are exceptions assigned and tracked? What run records are retained? Who can change rules, prompts, routing, or thresholds, and how will changes be tested before use?

    Clearpath describes a separate control envelope for recording permissions, input and output contracts, validation, approvals, logging, uncertainty handling, reversibility, and execution controls around a segment’s primary disposition. Its assessment also records dependent systems, data sources, and unresolved integration contracts before production start. Clearpath states that its product can enforce owner-configured approval checkpoints and retain a run record of workflow steps and tool actions. Those capabilities, where applicable, do not replace organization-specific design and control decisions.

    For AI-enabled steps, NIST presents its AI Risk Management Framework as a voluntary framework for incorporating trustworthiness considerations through design, development, use, and evaluation. Its Core organizes outcomes and actions under govern, map, measure, and manage. NIST cautions that these are not a mandatory checklist or fixed sequence, and frames risk management as continuous across the lifecycle.

    Use that framing operationally: govern by clarifying owners and authority; map the workflow, data, affected parties, and failure modes; measure whether the segment behaves as intended against organization-defined criteria; and manage findings through changes, escalation, or withdrawal of authority. Include the people who operate and receive the work. Training should explain not just the new steps, but when to override, escalate, and report a problem.

    How a hypothetical invoice-exception workflow can use different dispositions

    Consider a hypothetical invoice-exception workflow. This is an illustration of scoping, not evidence of results or a template for a particular organization.

    Validation segment. A received invoice is checked for required fields and matched against specified records. If the required inputs, matching logic, and resulting status update are fully defined, this segment may be a candidate for deterministic automation. Missing data or a failed match should route to a defined exception path rather than being forced through.

    Exception segment. A mismatch may involve an email explanation, a document, or other unstructured material. A bounded AI-assisted step could help extract candidate details or categorize the reason for review, provided its permitted output and system access are fixed. It should not decide whether an exception is acceptable when that decision requires material judgment.

    Payment segment. Releasing payment may require a person with appropriate authority. The workflow can prepare a complete review package, show validation and exception status, and route it to an approval checkpoint. The human approver remains responsible for the authorization decision.

    The lesson is structural: validation, interpretation, exception handling, and authorization need not share one disposition. Segmenting the workflow lets the team automate defined work without pretending that every downstream decision is equally defined.

    FAQ: practical questions before assessing a workflow for automation

    What makes a manual workflow a good candidate for business process automation?

    A good candidate is usually repeatable, has clear inputs and rules, has a known exception path, and has an accountable owner. If the work changes often, depends on unstructured input, or needs frequent judgment, it is less likely to fit unattended automation without extra controls.

    When should a workflow stay human-led instead of fully automated?

    Keep the human decision when the work involves material judgment, ambiguous cases, or authorization that should remain with a person. Human review is also appropriate when the exception path is not clear enough to stop or escalate safely.

    How do deterministic automation and AI-assisted automation differ?

    Deterministic automation is for steps where the inputs, rules, and permitted action are fully defined. AI-assisted automation can help interpret unstructured input or prepare a structured handoff, but its permissions and outputs should stay fixed and limited.

    What should I document before automating a workflow?

    Document the trigger, required inputs, deterministic rules, judgment points, permitted actions, exception or escalation paths, accountable owner, and the systems and data sources involved. Also note any unresolved integration contracts or approval questions before production design.

    What governance controls matter most when AI is involved in a workflow?

    Limit the systems and functions the AI can access, use the minimum permissions needed, validate outputs before consequential use, route uncertain cases to a named human owner, and keep records of steps and tool actions. For consequential actions, use human approval where needed.

    Why is workflow mapping important before choosing automation software?

    Workflow mapping shows how work actually moves across tasks, handoffs, decisions, systems, and people. It helps reveal bottlenecks, exceptions, ownership gaps, and controls so you can decide what should be automated, assisted, or kept human-led.

    Map one workflow and record the controls that remain unresolved

    Choose one manual workflow with a clear trigger and outcome. Map the current path first, then divide it into bounded segments. For each segment, document the trigger, inputs, rules, judgment point, permitted action, exception route, and accountable owner. Assign a provisional disposition—deterministic automation, bounded AI assistance, or human decision—and list what remains unknown.

    A useful first scope produces both candidates and constraints: missing data, unstable rules, unclear authority, unresolved integrations, unowned exceptions, and controls that must be designed before production. Do not treat those findings as project failure. They are the information needed to avoid automating ambiguity.

    Bring one workflow to a Clearpath assessment and leave with a scoped Boundary Map and its unresolved controls.


  • How to Prepare for an Employment Discrimination Attorney Consultation

    How to Prepare for an Employment Discrimination Attorney Consultation

    What an initial employment-law consultation can and cannot clarify

    An initial employment-law consultation can begin with organized facts rather than a demand for an immediate verdict. It can help identify the questions raised by a workplace situation, the facts that still need clarification, the records that may matter, and sensible next questions. It is not a substitute for a full factual and legal review.

    Before an engagement, information is general only. According to Austin Workplace Counsel, it does not establish an attorney-client relationship, representation, a claim, or a likely outcome. A consultation is therefore best approached as a structured discussion: what happened, when it happened, who was involved, what records exist, and what decision needs attention now.

    That distinction matters. Workplace concerns can involve conduct that feels unfair, a policy dispute, a performance issue, a leave question, an accommodation request, a discipline decision, or a possible discrimination concern. Labels alone do not resolve what rules apply. A clear packet helps a lawyer or legal professional understand the sequence without asking you to prove your own case before the conversation starts. Austin Workplace Counsel uses an intake packet to identify missing facts and possible next questions—not to determine representation or predict a result.

    Your goal before the meeting is not to reach a legal conclusion. It is to make the underlying information easier to examine. A concise, candid account—including facts that seem unfavorable, uncertainty about dates, and records you cannot locate—is more useful than a polished theory built on assumptions.

    Start with the location of the events and any immediate decision or deadline

    A search for a “Seattle” employment discrimination attorney does not itself determine which law, agency, court, or procedure may be relevant. Start instead with the facts that locate the matter: where you worked, where the relevant decisions were made or communicated, where the employer operates, and whether your work arrangement crossed state lines. Rules, coverage questions, and timing requirements can vary by jurisdiction and by the circumstances of the employment relationship.

    The approved service context is Austin, Texas, while the keyword is Seattle-focused. Do not assume that Washington or Seattle law applies merely because those words appeared in a search. Conversely, do not assume that the work location alone answers every jurisdiction question. Remote work, multi-state employers, travel, and the location of a decision-maker can make the analysis fact-specific.

    Do not guess at a filing deadline or assume that a rule from another state applies to an Austin, Texas workplace matter. If you may need to make a workplace decision, respond to an employer communication, preserve information, or consider an agency process, flag that issue promptly and confirm current requirements with an authoritative agency or qualified local counsel. This article does not provide a deadline, coverage determination, or individualized legal advice.

    Put urgency at the top of your consultation packet. In one or two sentences, state the next workplace event or decision you are facing—for example, a meeting, response request, proposed agreement, return-to-work issue, disciplinary action, or separation date. Include the date and the source of that information. Austin Workplace Counsel asks prospective clients to identify any immediate workplace decision or deadline because, the firm says, that helps prioritize what should be discussed first.

    A useful first-page summary might include:

    • Your job title, employer, work location, and employment status as you understand them.
    • The location or locations where the key events occurred.
    • The immediate decision, meeting, or deadline you are concerned about.
    • The date you learned of it and the document, message, or person that communicated it.
    • A short statement of what you want to understand in the consultation.

    This is an organization tool, not a legal conclusion. It allows the consultation to begin with the most time-sensitive practical question.

    Build a dated, fact-first workplace timeline

    A dated timeline is the backbone of a productive consultation. Build it in chronological order, beginning with the earliest event that may provide context and continuing through the most recent development. Use exact dates when you have them. If you do not, say “approximately” and identify the basis for your estimate, such as a calendar entry, pay period, meeting invitation, or holiday.

    For each entry, separate the observable event from your interpretation of it. Record who was involved, what was said or done, how it was communicated, and what happened next. If there is a document or message, note its name, date, and where it is stored. Austin Workplace Counsel asks prospective clients to prepare a dated event timeline and identify the people involved; the firm says date order helps distinguish the sequence of events from later interpretation.

    A practical format is:

    • Date and time: Include an estimate if necessary.
    • People involved: Name the decision-maker, manager, colleague, HR representative, or other participant, with job titles if known.
    • Event: Describe the action or communication in plain language.
    • Source: Identify the email, chat, letter, meeting, policy, calendar item, or personal recollection connected to the entry.
    • Follow-up: Note what happened afterward, including any report, response, schedule change, discipline, or other action.
    • Open question: Mark facts you do not know rather than filling gaps with assumptions.

    For example, “March 4—manager told me in a video meeting that my shift would change; attendees were A and B; calendar invitation saved; I asked for the reason in an email that afternoon.” That is more useful than “my manager began treating me differently.” The latter may be an important concern, but it becomes easier to discuss when it is linked to specific events, comparisons, communications, and dates.

    Keep your timeline factual even when the experience was upsetting. You can include your understanding of why an event mattered, but label it as your understanding. A consultation can then explore what additional facts or records might clarify the issue. Avoid turning the timeline into an argument: do not omit inconvenient events, assign motives you cannot support, or describe disputed matters as established facts.

    After drafting it, compare the timeline against your calendar and records. Mark contradictions instead of silently choosing the version that best supports your concern. The point is not perfect memory; it is a transparent starting point for questions and verification.

    Organize records without changing, deleting, or improperly accessing them

    Bring order to the information you already possess or are authorized to access. Preserve original documents and messages where possible, and keep a simple inventory rather than trying to create a polished narrative from memory. Austin Workplace Counsel asks prospective clients to preserve original materials and distinguish direct records from recollection. The firm notes that originals retain wording and surrounding context for review, while separating records from recollection can expose factual gaps instead of filling them with assumptions.

    Create two folders or lists. The first is direct records: emails, text messages, chat messages, letters, performance reviews, schedules, policies, meeting invitations, pay records, notes you made at the time, and other materials you lawfully possess. The second is recollection: your memory of conversations, verbal comments, meetings, and events for which no record is available. For each item, note the date, participants, and how it connects to your timeline.

    Preservation does not mean altering files, editing messages, deleting communications, accessing accounts you are no longer authorized to use, forwarding confidential employer material without considering your obligations, or taking information you do not have a right to possess. If you are uncertain whether you may access, copy, or retain a particular item, identify it in your inventory and ask about it during the consultation rather than acting first.

    Avoid “cleaning up” materials. Do not add explanatory text inside an original message, crop away context, rename a file so extensively that its source becomes unclear, or combine separate items into a document that looks like an original. A separate index is safer and more useful. It can say: “Email from supervisor, May 12, subject line ‘Schedule,’ saved in personal inbox” or “My recollection of conversation after team meeting, approximate date June 2.”

    If a record is missing, say so. A missing document is a fact to note, not an invitation to reconstruct its wording as certain. Also note records that may exist elsewhere, such as an employer system, without attempting unauthorized access. Separating records from recollection can make factual gaps visible and make it easier to see what should be verified.

    Understand the information a Texas discrimination complaint may require

    For a limited Texas process example, the Texas Workforce Commission Civil Rights Division states that employment discrimination generally exists when an employer treats an applicant or employee less favorably merely because of race, color, religion, sex, age over 40, national origin, or disability. It identifies hiring, firing, promotions, harassment, training, wages, and benefits as workplace situations to which employment discrimination can apply.

    That general description does not determine whether discrimination occurred in any particular situation, whether an employer or worker is covered, or whether a complaint is appropriate. Those questions depend on facts and applicable law. It does, however, show why a fact-first packet is useful.

    The Texas Workforce Commission Civil Rights Division says it requires specific information to process a complaint. Its listed information includes the identities of involved parties, a description of the specific employment action or conduct, and a stated causal connection to a protected characteristic, such as race, sex, age, or disability. Your timeline and record inventory should make those categories easier to discuss without forcing you to make unsupported conclusions.

    In practical terms, organize information around three questions:

    1. Who was involved? List the employer, relevant managers, HR contacts, decision-makers, and potential witnesses. Do not speculate about what another person knew or intended; identify what you observed and the basis for it.
    2. What specific action or conduct occurred? Describe the hiring decision, discipline, termination, promotion decision, comment, schedule change, pay action, training issue, benefit issue, or other event with dates and records where available.
    3. Why do you connect it to a protected characteristic? State the facts that lead you to raise the question. That might include language used, the timing of events, a stated reason, or another concrete circumstance. It is acceptable to say that you do not know the answer and want to understand what additional information would matter.

    The division also states that it has authority to investigate discrimination charges against employers covered by law and that its investigation role is to assess allegations and make a finding. Current filing procedures, coverage conditions, and timing requirements should be confirmed directly with the relevant authority or qualified counsel because they may change and can depend on jurisdiction. This Texas example should not be treated as a conclusion about a Seattle, Washington matter or about your own eligibility.

    Prepare focused questions about process, scope, fees, and next steps

    A consultation is easier to use when you arrive with a short written question list. Prioritize the questions that affect what you need to do next, then ask about the working relationship if further services may be discussed. Austin Workplace Counsel asks prospective clients to prepare questions about who would handle future work, proposed scope, fees, communication, documents still needed, and the next decision after the consultation.

    Consider asking:

    • Based on the locations and facts I have described, what jurisdiction or process should I confirm?
    • Are there timing issues or immediate decisions I should verify promptly with an agency or local counsel?
    • What facts are missing from my timeline, and what should I avoid assuming?
    • Which records should I preserve, and are there limits on how I may access or retain workplace materials?
    • What confidentiality considerations should I understand before sharing information?
    • What would a proposed scope of work cover, if any future work is offered?
    • Who would handle future work, and how would communication be managed?
    • How are fees and costs discussed, and what information is needed before any engagement decision?
    • What documents would be useful to gather next?
    • What is the next decision I should make after this consultation?

    Write answers down during or immediately after the discussion. If a question is not answered because more facts are needed, add it to your follow-up list. A good outcome from an initial discussion may be a clearer set of questions and a better-organized record—not a definitive answer. Ask what you should do while awaiting clarification, especially if an employer has requested a response or a relevant date is approaching.

    FAQ: Practical questions before you contact an employment discrimination attorney

    What should I bring to an employment discrimination consultation?

    Bring a dated timeline, the names of the people involved, and any original emails, texts, letters, schedules, policies, pay records, or notes that help show what happened. If something exists only in your memory, separate that from documents so the discussion stays factual.

    How do I know if my situation involves discrimination or another workplace issue?

    You do not need to label it before the consultation. An initial discussion can help identify missing facts and possible next questions about the situation. The key is to describe the events clearly and honestly.

    Should I assume Seattle or Washington law applies because of the keyword?

    No. Applicable rules depend on the facts, including where the work was performed and where the key decisions were made. If your matter is in Austin, Texas, confirm the correct jurisdiction and any timing issues with current authoritative sources or qualified local counsel.

    Why does a dated timeline matter so much?

    A timeline helps separate the sequence of events from later interpretation. It makes it easier to see who was involved, what was said or done, and what records support each event. That gives the consultation a clearer starting point.

    What records should I avoid changing before the consultation?

    Do not edit, delete, or “clean up” original messages or documents. Preserve the original wording and context, and keep a separate inventory of what you have. If you are unsure whether you may access or keep a particular record, ask about it during the consultation instead of acting first.

    What questions should I ask during the consultation?

    Ask about the likely jurisdiction or process, any immediate deadline or decision, what facts are still missing, what records to preserve, confidentiality concerns, fees, who would handle any future work, and what the next step should be after the meeting.

    Does an initial consultation mean I have a case or will be represented?

    No. The intake and consultation process is general and does not itself establish a claim, representation, or a likely outcome. Its main purpose is to identify missing facts and possible next questions.

    Request a consultation with your organized packet

    You do not need a perfect legal theory to prepare well. Start with the immediate decision or deadline, a dated timeline, a list of people involved, an inventory of original records, separate notes for recollection, and a concise list of questions. That packet gives an initial consultation a practical starting point and makes missing information easier to identify.

    Austin Workplace Counsel provides employment law consultations and uses intake materials to identify missing facts and possible next questions. The intake process itself does not establish a claim, representation, or a likely outcome. Keep jurisdiction and timing questions visible, and confirm current procedural requirements promptly with appropriate authoritative sources or qualified local counsel.

    Prepare for an employment-law consultation by organizing the timeline, documents, and questions needed for an initial discussion.